Does Cosigning Build Credit
You've probably heard someone say, "Hey, just cosign for me?" It sounds simple enough, like lending your umbrella to a neighbor. But before you hand over your good credit repu...
You've probably heard someone say, "Hey, just cosign for me?" It sounds simple enough, like lending your umbrella to a neighbor. But before you hand over your good credit reputation, let's talk about what that actually means for you.
Cosigning means you're telling the lender, "If they don't pay, I will." You're basically standing beside someone like a buddy at a karaoke bar singing backup. The stakes? Your financial life.
Does It Actually Build Your Credit?
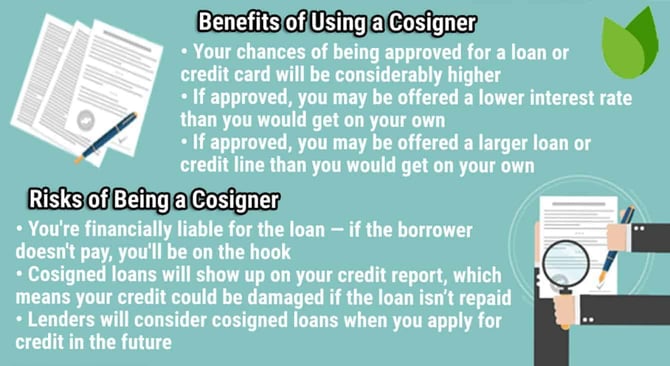
Here's the good news — yes, it can build your credit, but there's a catch. The account shows up on your credit report too, so when payments are made on time, both you and your cosignee benefit. Think of it like a potluck dinner where everyone eats well.
Must Read
However, it only works if the borrower actually pays. If your roommate forgets to make that car payment three months in a row, your credit score takes the hit too. Suddenly that potluck dinner looks a lot less fun.
The Real-World Example
Imagine your younger sibling wants to buy their first apartment. They don't have enough credit history yet, so they ask you to cosign. Everything goes smoothly, rent gets paid, and your credit gets a little love from the positive report.
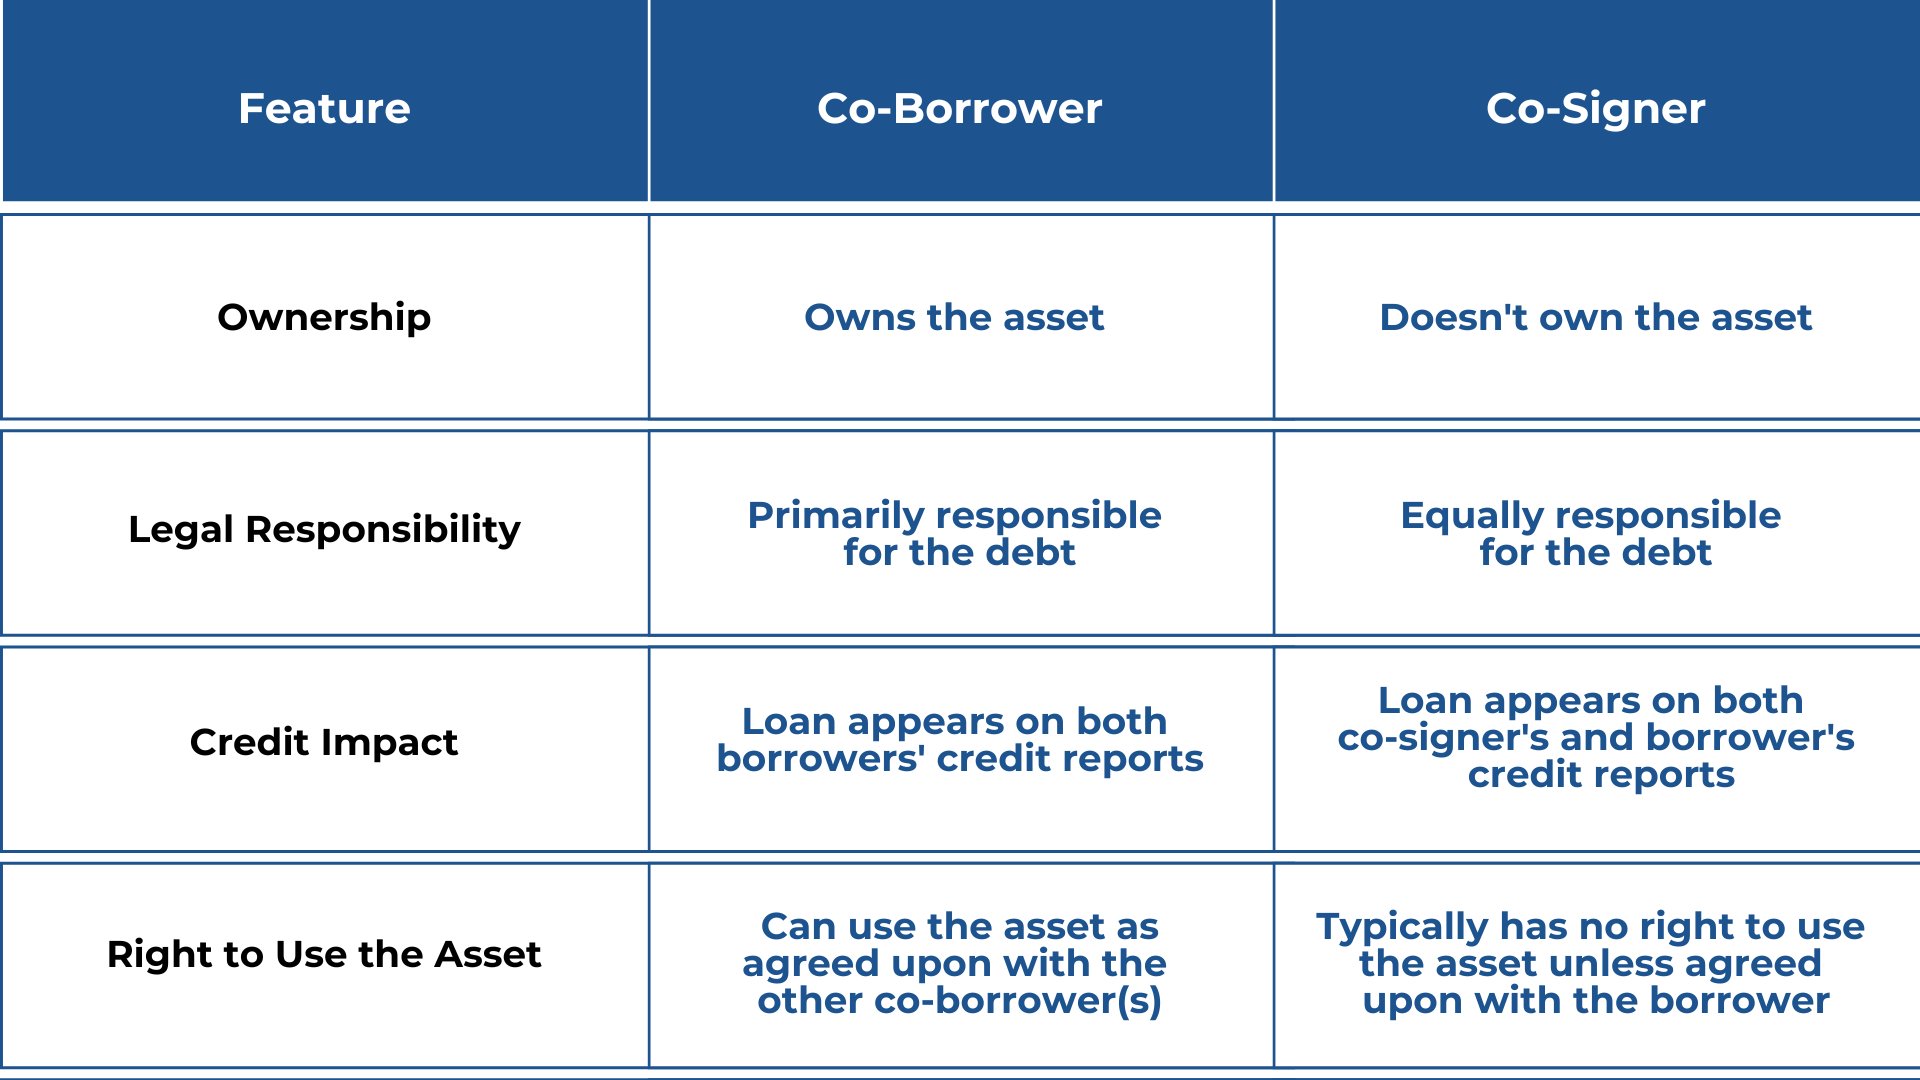
 Cosigner - Meaning, Requirements, Vs Co-Applicant/Guarantor
Now flip the script. What if three months later they lose their job and stop paying? You're on the hook for the full amount, and your credit report reflects every missed payment. Ouch.
Why You Should Actually Care
Your credit score is kind of like your financial reputation at a party — it follows you around. A good score means lower interest rates on mortgages, car loans, and even some job opportunities. A damaged one? That could cost you thousands of dollars over the years.
So when someone asks you to cosign, it's not a casual favor. You're tying your financial future to theirs, whether you realize it or not. That's definitely worth a second thought.
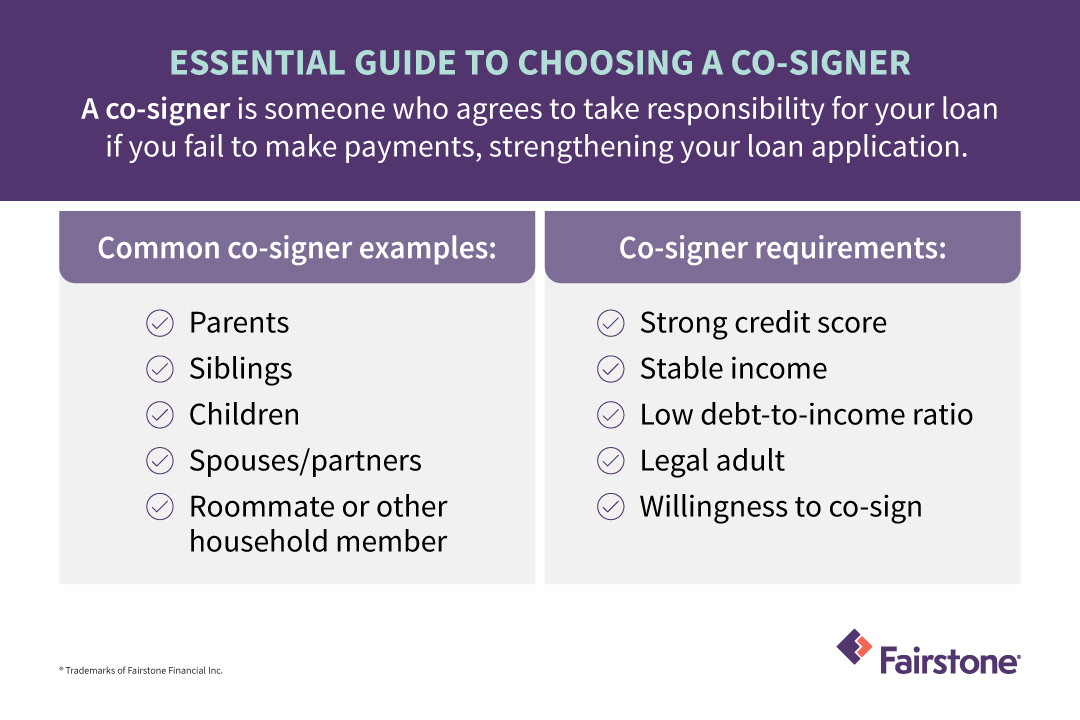 Why Do I Need a Co-Signer For My Loan? | Fairstone
Tips Before You Cosign
First, make sure you'd feel comfortable paying that debt yourself. If the answer is a nervous laugh and sweaty palms, probably not a good idea. Trust is nice, but budgets matter more.
Second, ask to be added on all payment notifications so you can catch problems early. Think of it as keeping an eye on the shared potluck so nobody shows up with expired leftovers. 💀 No, just kidding or expired groceries.
 Best Credit Cards with Cosigner in 2024 | Credello
Lastly, remember that the account will stay on your credit report until it's fully paid off. That's a long-term commitment you're agreeing to — sometimes seven to ten years on that student loan. Cosigning is easy to do but not easy to undo.
The Bottom Line
So yes, cosigning can build your credit if everything runs smoothly. But it's a two-way street — you get the upside of good behavior, and you share the downside of bad behavior too. Either way, just go in with open eyes and a solid understanding of what you're agreeing to.
Your credit is a precious thing that you've worked hard to build. Guard it the way you'd guard your favorite coffee mug — with setting boundaries. When in doubt and trust the relationship but also protect yourself — because future you will definitely thank you.