What Is Insurable Risk And Non Insurable Risk
Let’s be real—insurance can feel like a dry topic, but understanding what makes a risk insurable versus non-insurable is actually a superpower for your wallet and peace of min...
Let’s be real—insurance can feel like a dry topic, but understanding what makes a risk insurable versus non-insurable is actually a superpower for your wallet and peace of mind. It’s the secret sauce that separates stressful guesswork from smart financial safety nets. Whether you’re a freelancer, a parent, or just someone who hates surprise expenses, this knowledge helps you decide where to put your hard-earned cash.
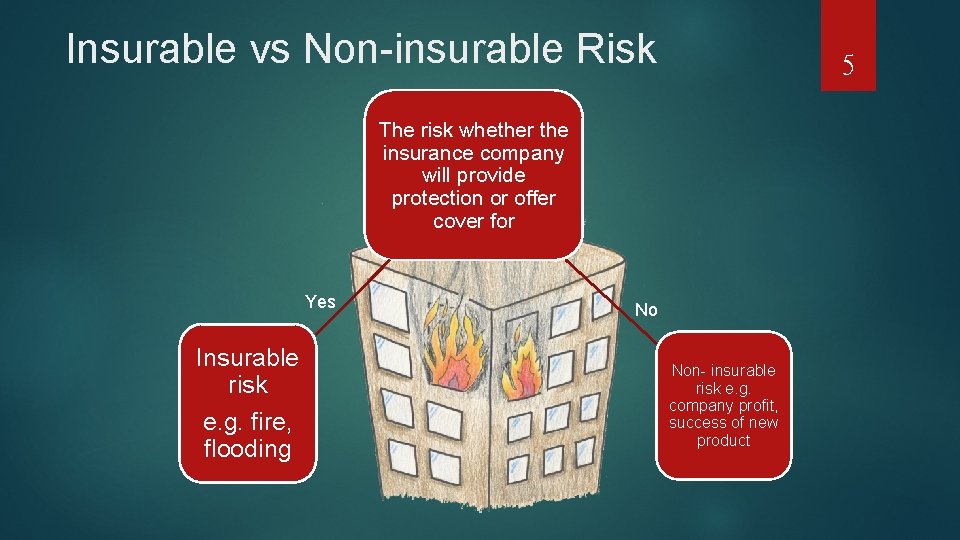
Why does this matter? Because insurable risks—like a car crash, a house fire, or a health scare—are things you can plan for. They’re predictable in a statistical way, meaning insurance companies can crunch the numbers and offer you a fair price. For individuals and families, this means financial stability: a burst pipe won’t drain your savings, and a medical bill won’t wreck your future. Communities benefit too, because widespread insurance reduces the need for government bailouts after disasters.
Non-insurable risks, on the other hand, are the wild cards—things like a sudden market crash, a new technology making your business obsolete, or even your own bad habits. These are too unpredictable or too catastrophic for any insurer to cover. Think of a nuclear war or a slow, creeping inflation: no one can price that. Knowing this difference saves you from wasting money on a policy that won’t pay out, and pushes you to self-protect through savings or diversification.
Must Read
Real life? A classic example: car insurance is insurable because accidents have decades of data. But “loss of income due to a global pandemic”? That’s non-insurable for most small businesses—it hit too fast and too wide. Another common one: life insurance covers death (sad but predictable), but it won’t cover a “voluntary skydiving accident” if you’re an extreme sport rookie without a rider. These examples show why you read the fine print before signing.
How to apply this easily? Start by listing your biggest fears—health, home, car, business. Ask: “Is this a common, calculable event?” If yes, it’s probably insurable—get a quote. If it’s rare, unethical, or system-wide (like a stock market crash), skip the insurance and build an emergency fund instead. Also, always check for exclusions: that “act of God” clause might turn a flood into a non-insurable mess for your home.
 Distinguish between insurable risk and non-insurable risk - Brainly.in
Another tip: for non-insurable risks, hedge your bets. If your job could be automated, learn a new skill. If your city might flood in a decade, move your valuables higher up. Insurance only covers the now; your adaptability covers the what if.
So here’s the takeaway: Insurable risk is your friend—it’s a safety net you can afford. Non-insurable risk is a wake-up call to build resilience elsewhere. By knowing the difference, you stop overpaying for fake safety and start spending on what truly protects you. That’s a win for your bank account, your family, and your sleep schedule.

