Can I Freeze My Bank Account
Let’s be honest—when you hear the words “freeze your bank account,” your first thought is probably panic. You imagine a cold, icy block of concrete where your money used to be...
Let’s be honest—when you hear the words “freeze your bank account,” your first thought is probably panic. You imagine a cold, icy block of concrete where your money used to be. But freezing a bank account isn’t always a crisis; sometimes, it’s just a smart pause button.
Think of your bank account like a favorite jar of cookies. Normally, you reach in whenever you want. But what if you’re trying to save for a big trip, or you’re worried you’ll accidentally spend your rent money on takeout? Freezing the account is like putting the lid on tight—you can’t get in until you decide to thaw it.
So, can you actually freeze your own account?
Short answer: Yes, you can, but it’s usually called a “temporary freeze” or a “hold.” Many banks let you do this through their app or by calling them. For example, if you lose your debit card, you can freeze the account instantly to stop any unwanted charges.
Must Read
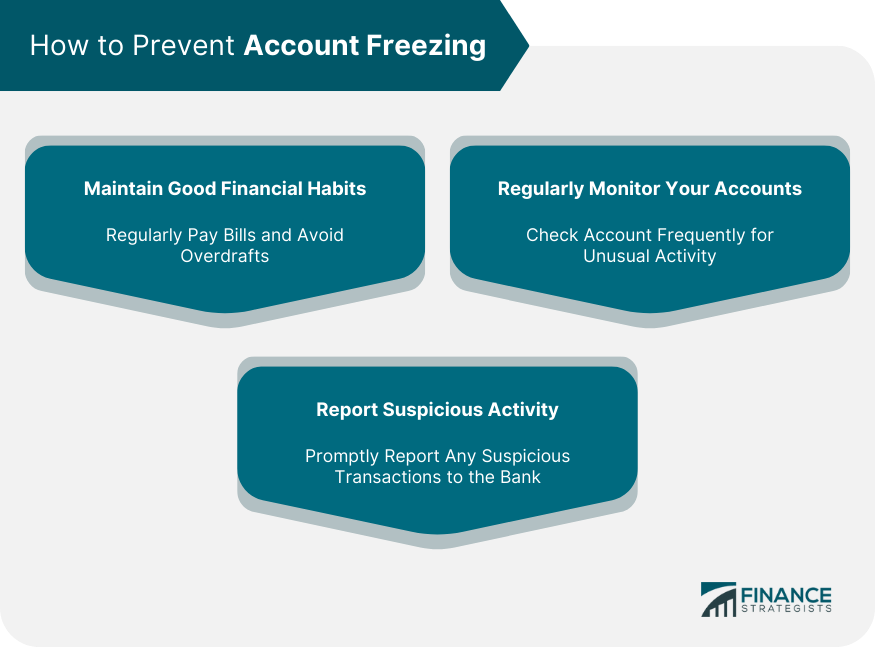
But here’s the fun part: not all freezes are your idea. Sometimes the bank freezes your account for reasons like suspicious activity or a court order. Don’t worry—that’s rare, and they usually call you to sort it out.
Why should you care about freezing your account?
Imagine this: You’re on a beach vacation, and you realize you left your wallet at a café. If you had frozen your account right then on your phone, no one could touch your money. It’s like having a remote control for your wallet—pretty powerful, right?
Or picture this: You’re saving for a new bike, but every time you see a sale, you splurge. Freezing your savings account for a few weeks is like putting a sassy lock on your spending impulse. You can still pay bills from another account, but the “fun money” stays put.
 Bank Account Freeze New Government Guidelines And Relief For The Common Man
What about when someone else freezes it?
That’s the scary side. If a lender or the government freezes your account because of debt or a legal issue, it feels like getting snowed in without food. But here’s the good news: you’re not helpless. You can negotiate, show proof of hardship, or ask for a release. Most banks give you a heads-up first.
A friend of mine once had her account frozen because she bought a used car online from a seller who was flagged for fraud. She freaked out—but after a quick call, she proved she was the victim, and the freeze was lifted in two days. Moral of the story: always keep your contact info updated.
How to freeze your account safely
It’s easier than baking a frozen pizza. Log into your banking app, look for “security” or “card controls,” and hit “Freeze”. You might have to confirm with a text code. Then, when you’re ready, just tap “Unfreeze”—it’s that simple.
If you don’t have a smartphone, call your bank’s customer service. Say, “I’d like to place a temporary freeze on my account.” They’ll ask a few security questions, and bam—you’re on ice, but in a good way.
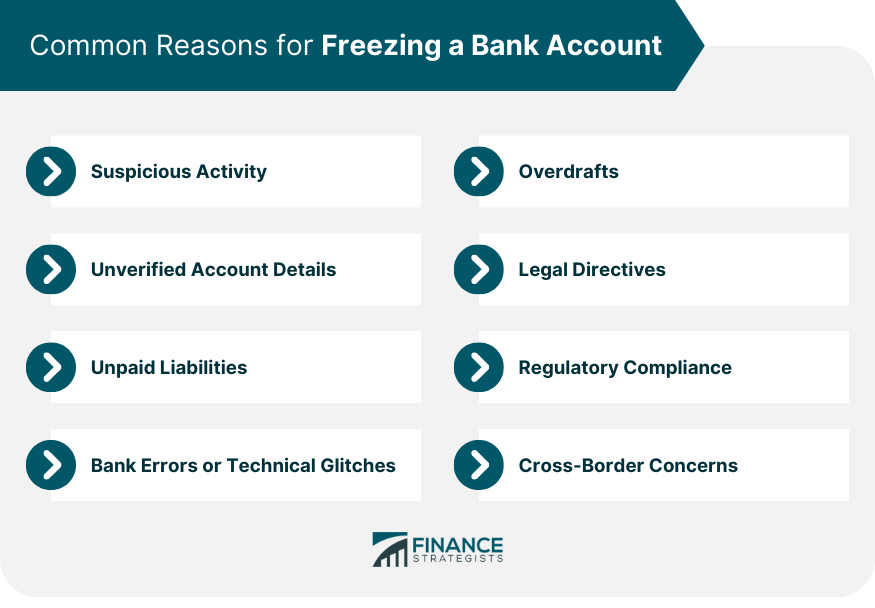 Frozen Bank Account | Definition, How It Works, Pros & Cons
Quick tips to avoid stress later
First, don’t rely on just one account. Have a separate checking account for daily spending and a savings one you can freeze without messing up your bills. Think of it like having two pantries—one for snacks, one for emergency canned beans.
Second, set a reminder to unfreeze if needed. Forgotten freezes can bounce payments or make you miss Netflix night. That’s a tragedy no one needs.
The bottom line
Freezing your bank account isn’t scary—it’s a tool. Use it to protect yourself from fraud, curb a shopping habit, or just take a break from your wallet’s noise. You’re the boss of your money, not the other way around.
So next time you’re tempted to overspend, or you lose your card in a couch cushion, remember: freezing is just a temporary time-out. Thaw it when you’re ready, and carry on with a smile.
