Credit Card Finance Charge Definition
Understanding how credit cards work has become one of the most empowering pieces of financial knowledge anyone can gain today. Many people enjoy the convenience and flexibilit...

Understanding how credit cards work has become one of the most empowering pieces of financial knowledge anyone can gain today. Many people enjoy the convenience and flexibility that credit cards offer for everyday purchases, travel, and emergencies. However, behind that convenience lies an important concept called the finance charge—and knowing exactly what it means can give you the confidence to use your card wisely. Whether you are a new cardholder or someone looking to manage debt more effectively, this definition is a cornerstone of smart money management.
A credit card finance charge is essentially the cost you pay for borrowing money from a credit card issuer. When you carry a balance from one billing cycle to the next—that is, when you do not pay your statement in full by the due date—the issuer applies an interest cost known as a finance charge. This charge is typically calculated based on a Annual Percentage Rate (APR) and the average daily balance of your account during the billing period. In simpler terms, it is the price of posting instead of paying at the time of your purchase.
The primary purpose of a finance charge is to compensate the credit card company for the risk it assumes by lending money to you. Unlike a debit card, which pulls funds directly from your bank account, a credit card represents an extension of credit. The issuer is essentially your lender for every transaction until you settle your balance. The finance charge also helps offset administrative costs, fraud losses, and the opportunity cost of the funds being lent to you instead of invested elsewhere. Understanding this purpose helps you see finance charges not as hidden penalties but as a fundamental part of the credit system.
Must Read
Finance charges benefit everyday life by giving consumers access to funds they may not have on hand. Consider a scenario where your refrigerator breaks down unexpectedly and replacement costs $800. If you do not have enough cash in your checking account, your credit card provides an immediate solution. You can purchase a new refrigerator today and pay it off over the next few months, adding only a modest finance charge in return for that temporary flexibility. Alternatively, if you pay $100 each month and clear the balance in eight months, the total finance charge at an APR of 20% would be roughly $60 to $70—a small price for solving an urgent problem without dipping into savings. When used adaptively, the finance charge system becomes a practical safety net for real-life situations.
On the flip side, ignoring finance charges can quickly become a burden. If you only make minimum payments on a $5,000 balance at 24% APR, for example, it could take over 15 years to repay the debt, and the total you pay in finance charges would far exceed the original amount borrowed. This is why paying more than the minimum—or ideally paying the full statement balance each month—remains the most effective way to enjoy credit card benefits without accumulating avoidance. Avoiding unnecessary finance charges means keeping more of your hard-earned money in your pocket where it belongs.
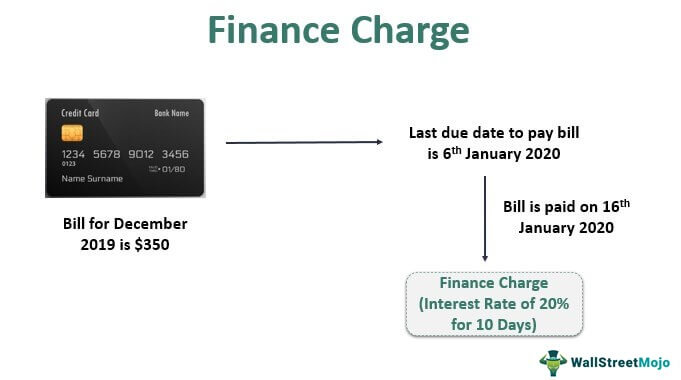 Finance Charge - What Is It, Formula, How To Calculate, Examples
Here are a few simple tips to explore this topic on your own. First, check your credit card agreement to identify your specific APR and how your issuer calculates the finance charge. Second, use an online finance charge calculator to experiment with different balance amounts and repayment plans to see how quickly interest can grow. Third, review your monthly statements carefully—the finance charge line item will show you exactly what you are paying each cycle. Finally, consider setting up automatic payments for at least the full statement balance to eliminate finance charges entirely while still enjoying all the rewards and perks your card offers.
In summary, the credit card finance charge is a straightforward yet vital concept that defines the cost of borrowing. By understanding how it is calculated, why it exists, and how it impacts your financial health, you transform from a passive cardholder into an intentional and informed consumer. With awareness and discipline, the finance charge becomes manageable—allowing you to leverage the power of credit while keeping your finances firmly under control.


