Does Being A Cosigner Build Credit
So there you are, sipping your latte, and someone drops the bomb: "Can you co-sign this loan for me?" You know, because they need your credit score as a co-pilot for their fin...
So there you are, sipping your latte, and someone drops the bomb: "Can you co-sign this loan for me?" You know, because they need your credit score as a co-pilot for their financial airplane. Before you grab a pen and proudly stamp your name on someone else's financial destiny, let's chat about what that actually does to your credit score.
First, What Even Is Co-Signing?
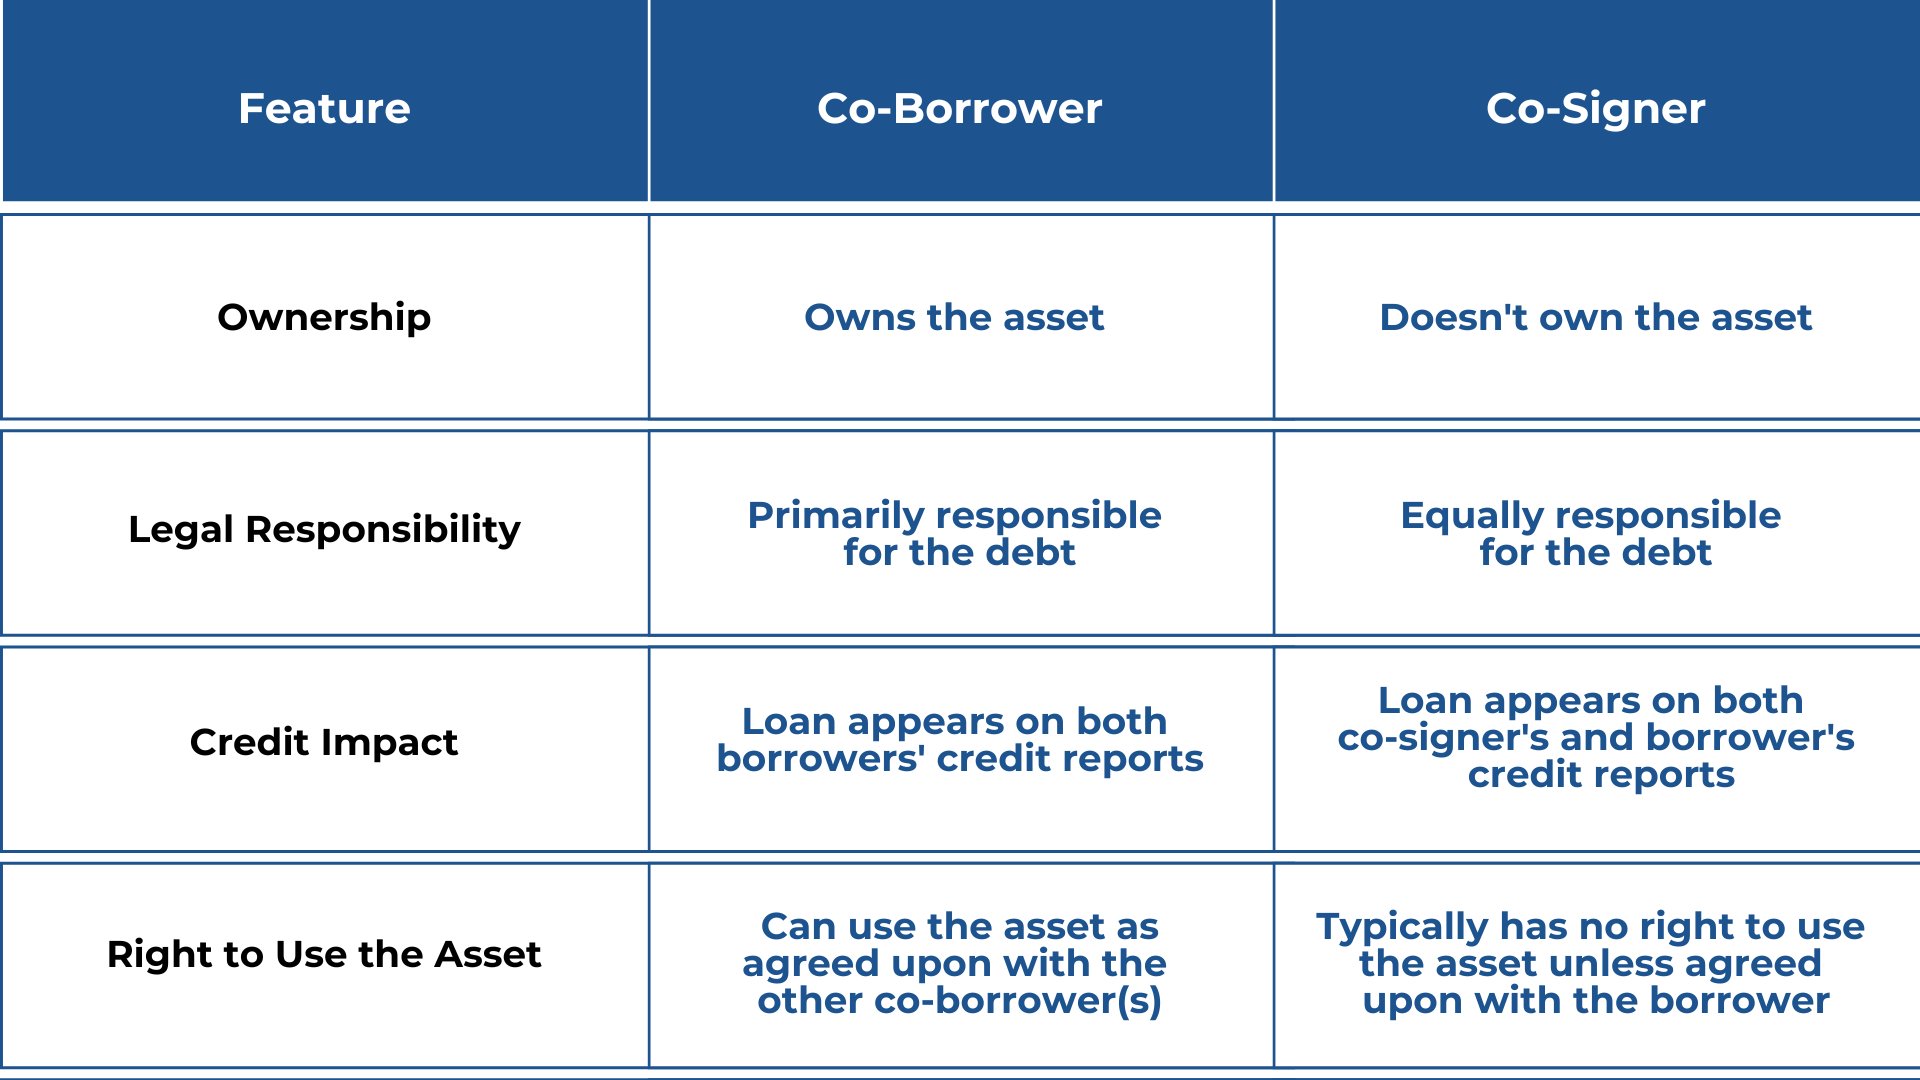
Think of co-signing as being the financial equivalent of a backup singer — you're technically part of the show, but everyone's watching the lead act. You agree to be legally responsible for the debt if the primary borrower pulls a vanishing act like a magician with a student loan. It's a big deal, people. No pressure, right?
Does It Build Your Credit? The Short Answer
Yes, but with a massive asterisk attached — the kind that has its own fine print. When the primary borrower makes payments on time, that positive payment history typically flows to your credit report too. So theoretically, your credit score can go up simply because someone else is being a responsible adult. What a time to be alive.
Must Read
Here's Where It Gets Tricky
The loan shows up on your credit report as if you took it out yourself, because — surprise — you kind of did. You're not a casual cheerleader; you're the person they call when things hit the fan. Your credit utilization ratio could also take a hit since you now carry a higher overall debt load. That extra debt floating around on your report can be like an uninvited cousin at Thanksgiving — just sitting there, making everything feel heavier.
The Downside Nobody Talks About (Until It's Too Late)
Here comes the plot twist: if the borrower misses a payment, YOUR credit score tanks too. Your flawless financial reputation gets dragged through the mud alongside someone who probably cancelled their alarm three times this week. One late payment could knock off dozens of points from a credit score you've worked years to build.
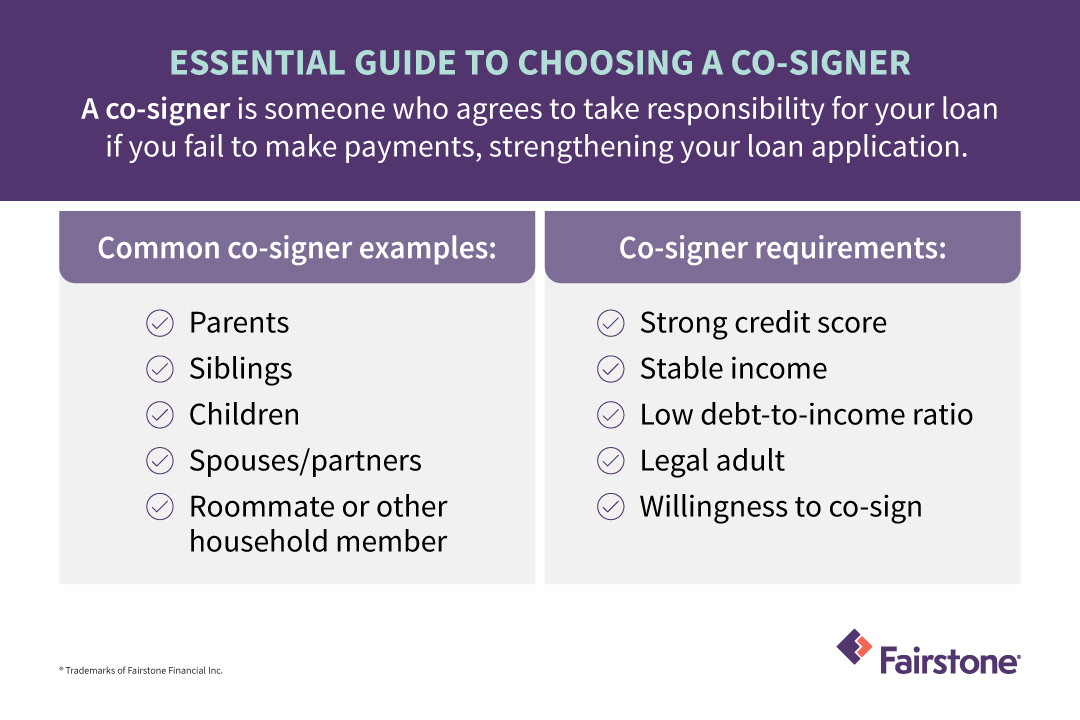 Why Do I Need a Co-Signer For My Loan? | Fairstone
What About Prequalification and Inquiries?
When you co-sign, the lender will likely run a hard inquiry on your credit, which can shave off a few points right out of the gate. It's ironic — a small temporary drop just for trying to help, while the borrower gets a shiny new loan. The things we do for love, friendship, or that one cousin who swears he'll pay you back this time.
The Debt-to-Income Ratio Headache
Your debt-to-income ratio — a number lenders care about deeply — gets less flattering when you co-sign. If you ever apply for your own mortgage or car loan, lenders might squint at that extra liability like it's a stain on your credit résumé. You might qualify for less than you did before, all because you were being generous.
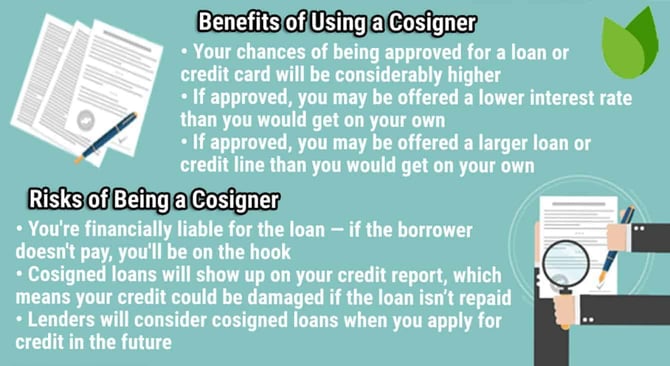 $6,000 Loans for Bad Credit in 2026 - BadCredit.org
How Long Does It Stick Around?
Here's a fun fact: the co-signed loan stays on your credit report for up to seven years after the last payment. SEVEN YEARS. That's longer than most people maintain a gym membership. The ghost of that co-signed loan could haunt your financial life longer than your junior prom photos.
So, What Should You Do?
If you decide to co-sign — and sometimes relationships and heart matter more than spreadsheet perfection — set clear expectations upfront. Ask the borrower to set up autopay so both of you don't have to rely on their memory, which, let's be honest, is probably the same memory that forgets charge their phone at night. Get everything in writing before you sign, because handshake deals are wonderful until one person forgets the handshake part.
The Verdict from the Café Table
Being a co-signer CAN build your credit — if, and only if, the borrower is financially reliable. It's like opening a joint savings account with a gambler: great in theory, potentially disastrous in practice. Your credit is your golden ticket, and lending it out deserves a little more thought than lending an umbrella. So sit with it, weigh the risks, and might I suggest another latte before you sign anything?