Does Cosigning Help Your Credit
Hey there, friend! Ever found yourself wondering if slipping your name on someone else’s loan is a sneaky shortcut to boosting your own credit score? Well, the answer isn’t a...
Hey there, friend! Ever found yourself wondering if slipping your name on someone else’s loan is a sneaky shortcut to boosting your own credit score? Well, the answer isn’t a simple yes or no, because cosigning is like borrowing a friend’s umbrella—sometimes it shields you from the rain, and other times it just gets you wet.
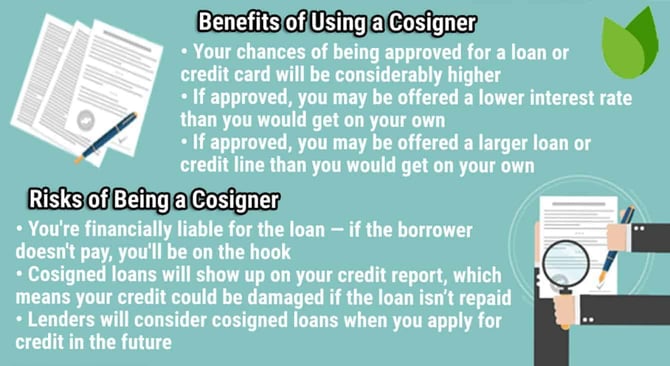
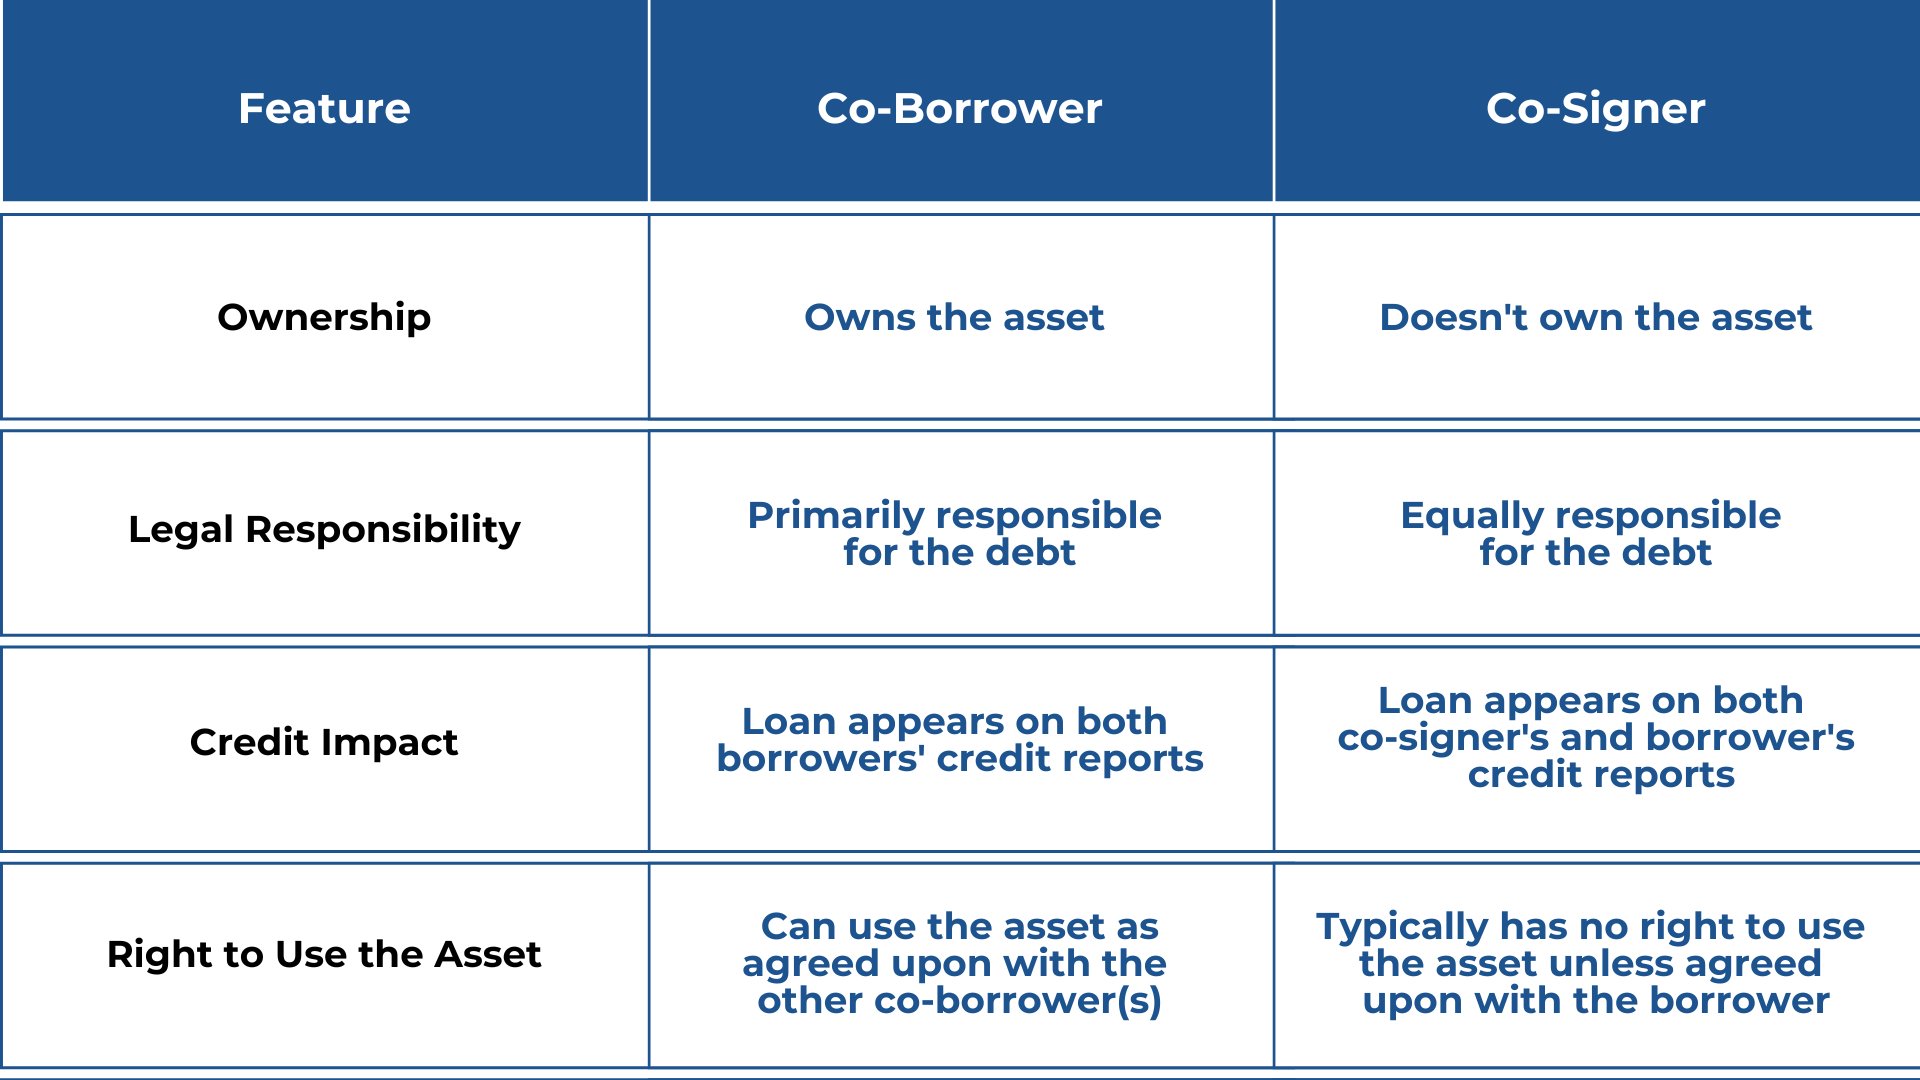
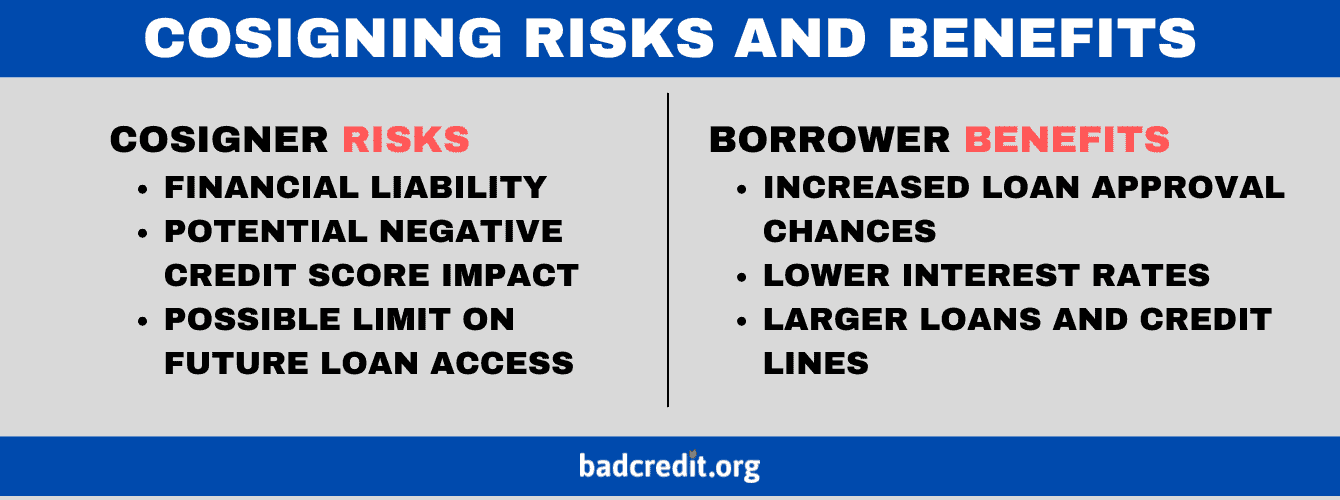
First off, when you cosign a loan, that obligation shows up on your credit report just like it does for the primary borrower. Your name becomes part of the official record, which means the lender can report late payments or defaults straight to your credit file. So, if the person you’re helping misses a due date, your score feels the pinch too.
On the flip side, a well‑managed cosigned loan can actually give your credit a little pep in its step. Positive payment history looks great on your report, potentially improving your debt‑to‑income ratio and showing lenders you’re a reliable borrower. It’s like adding a new, polished trophy to your credit shelf—as long as the trophy doesn’t tip over.
Must Read
Of course, there’s a catch. If the primary borrower decides to disappear like a magician’s rabbit, you’ll be left holding the bill—and, yep, that bill will haunt your credit history for up to seven years. And, let’s be honest, nobody wants a financial ghost popping up during a mortgage application, right?
So, does cosigning help your credit? It can, if you pick a trustworthy partner, keep an eye on the payments, and treat the loan like it’s your own. Think of it as a shared adventure: you’re both rowing the same boat, and as long as nobody starts splashing water overboard, you’ll both glide toward clearer skies.
 What is a Cosigner? How Lenders Reduce Risk for Borrowers with Credit
Before you sign on the dotted line, ask yourself a few playful questions: Do I actually know this person’s money habits? Am I comfortable with the idea of chasing down a payment if they slip up? And, most importantly, will the extra responsibility make my own financial life feel lighter or heavier? If you laugh at those prompts and still feel good, you’re probably in the clear.
In the end, cosigning isn’t a magic wand that instantly lifts your credit score, but it can be a useful tool when handled with care. Remember, it’s a partnership—not a one‑way ticket to a higher FICO. Treat the loan like a friendly game of tug‑of‑war, keep the rope taut, and you might just find both parties crossing the finish line with a big grin.
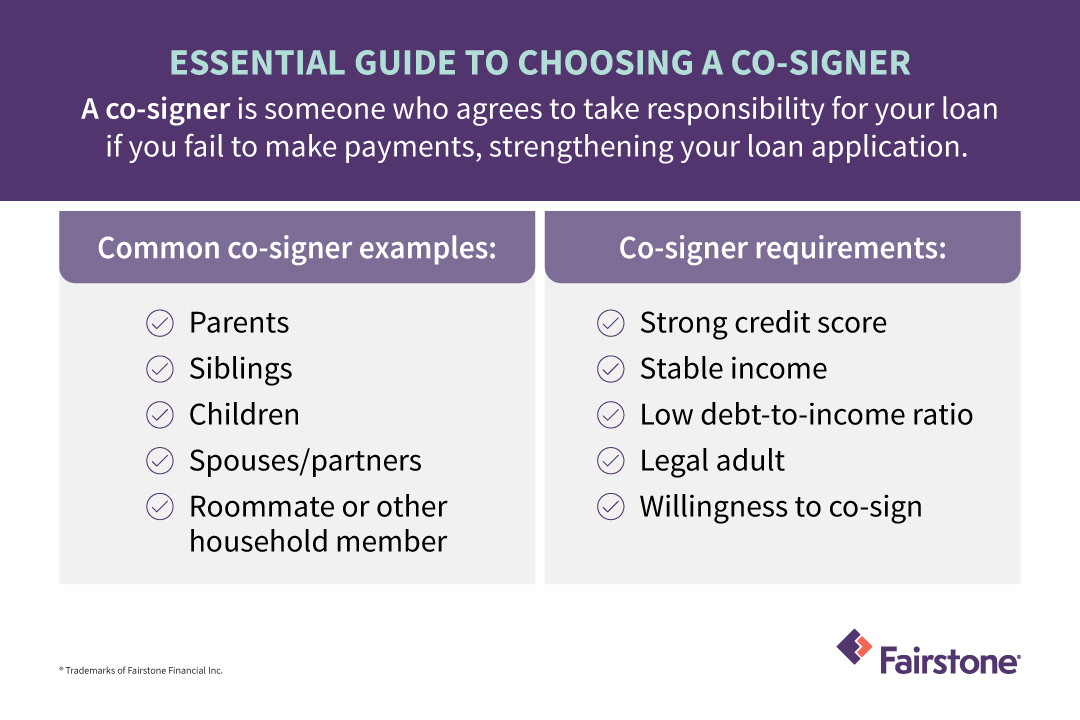 Why Do I Need a Co-Signer For My Loan? | Fairstone
Imagine you’re at a coffee shop, chatting with a friend who’s about to buy a car. You mention that you’ve nicely cosigned a small personal loan for a cousin, and suddenly your credit profile gets a subtle boost. The lender sees you as someone who can manage debt responsibly, which may open doors for better interest rates down the line. Of course, it’s still important to keep an eye on the loan’s progress, set up payment alerts, and regularly check your credit report for any surprises. A quick glance every few months can prevent any unwanted drama from sneaking up on you later.
So, the next time you’re asked to be a cosigner, picture yourself as a supportive sidekick rather than a secret hero. With a dash of caution, a sprinkle of communication, and a whole lot of optimism, you can help a loved one while giving your own credit a high‑five. And that, my friend, is a win‑win worth genuinely celebrating!