Does Cosigning Hurt Your Credit
For many people, cosigning a loan or lease represents one of the greatest acts of trust and generosity they can offer someone they care about. Whether it is a parent helping a...
For many people, cosigning a loan or lease represents one of the greatest acts of trust and generosity they can offer someone they care about. Whether it is a parent helping a young adult secure their first apartment, a sibling supporting someone rebuilding their financial life, or a friend enabling a small business venture, cosigning carries deep emotional and practical significance. It is valued precisely because it demonstrates that someone believes in another person's ability to succeed. However, before signing on the dotted line, many people pause and ask a critical question: does cosigning hurt your credit? Understanding the real impact is essential for making a smart, informed decision.
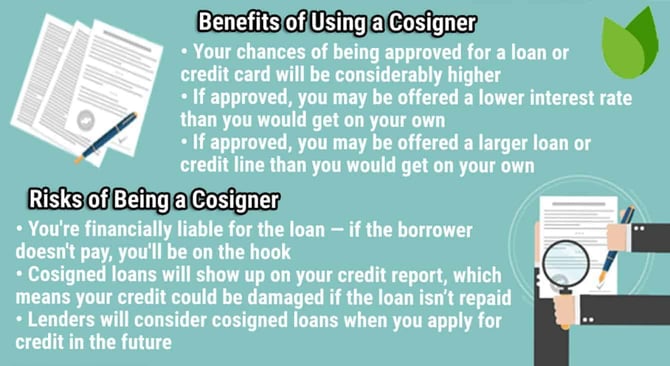
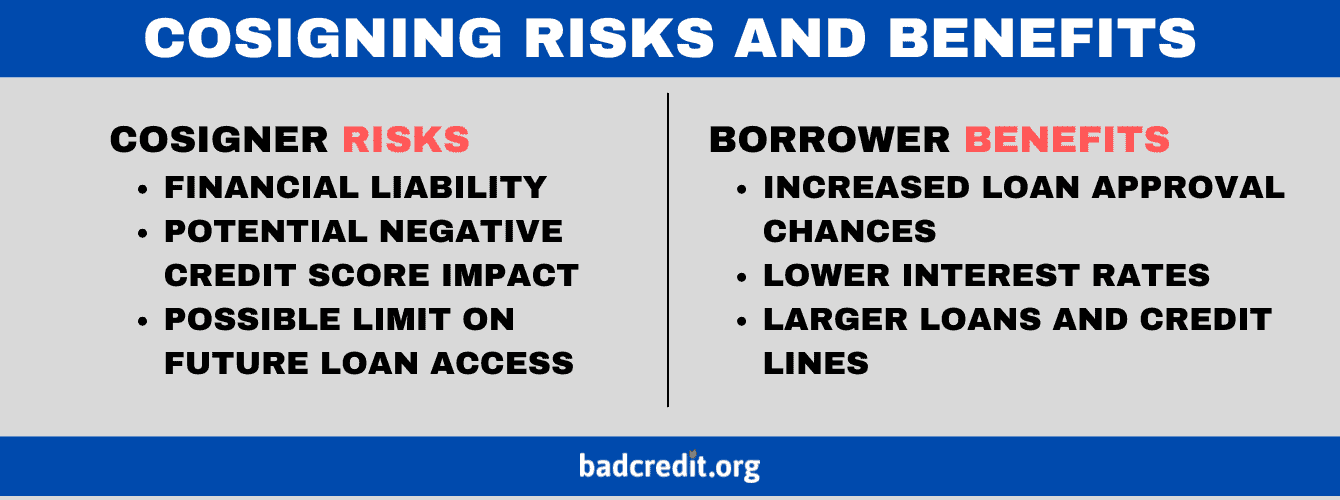
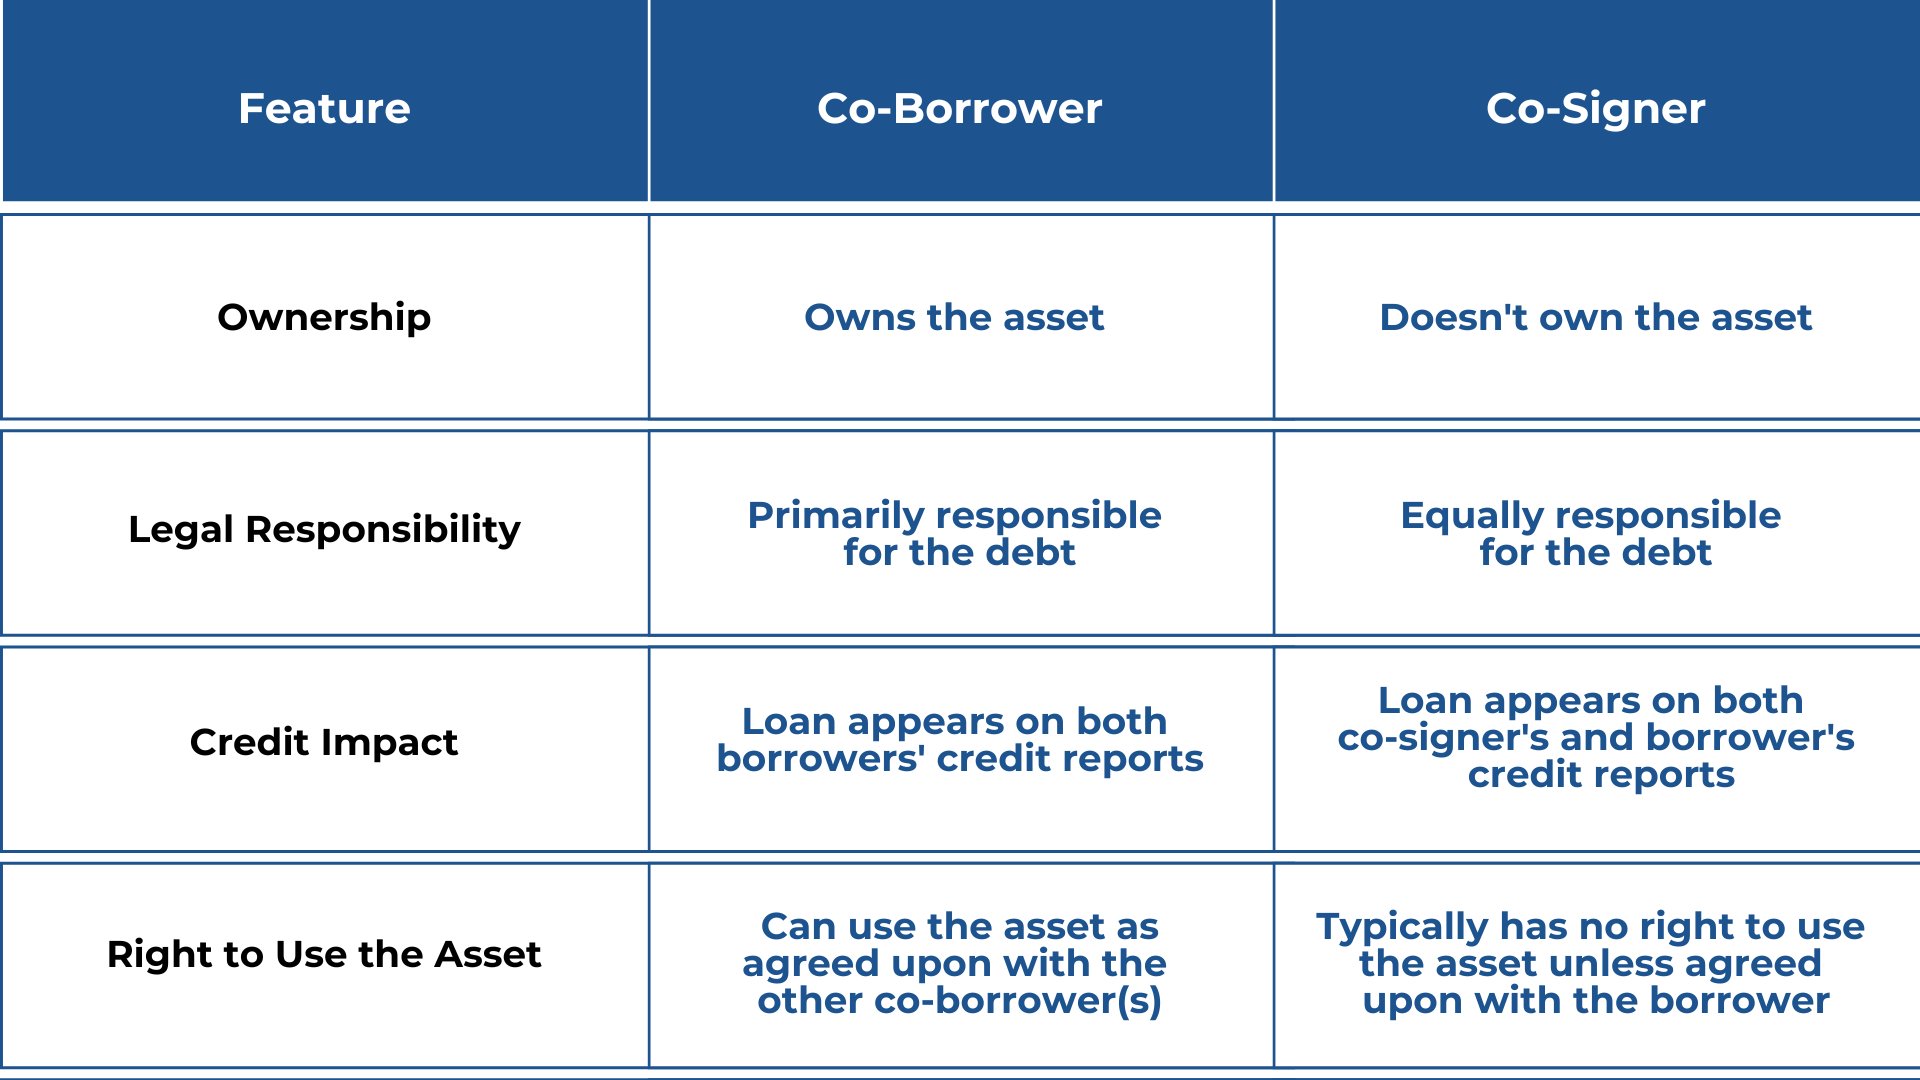
At its core, cosigning means agreeing to take equal legal responsibility for a debt if the primary borrower fails to make payments. Lenders require a cosigner when they see risk in the primary borrower's credit profile, and the cosigner's stronger credit essentially serves as a safety net. This arrangement benefits everyday life in meaningful ways: a college student with limited credit can get a car loan, a new rental applicant can satisfy a landlord who demands a high credit score, or a budding entrepreneur can access the capital needed to grow. The cosigner's role makes these milestones achievable for someone who might otherwise be turned away.
The good news is that cosigning does not automatically damage your credit score. In fact, if the primary borrower makes every payment on time diligently and consistently, your credit history can actually benefit from that additional record of responsible borrowing. Your credit utilization ratio may even improve if the new account lowers your overall utilization, and having variety in your credit mix can strengthen your profile over time. So the initial relationship between cosigning and credit is largely neutral to slightly positive, provided everything runs smoothly from day one.
Must Read
The danger emerges when payments go wrong. If the primary borrower falls behind, missing a single payment will be reported on your credit report as well, because the account is tied to your social security number. Multiple late payments or, worse, a default and subsequent collections action can cause your credit score to drop significantly. Lenders will factor this outstanding obligation into your debt-to-income ratio, meaning you might be denied or offered less favorable terms when you apply for a mortgage or refinance your own vehicle later. Essentially, a cosigned account can limit your borrowing power even when payments are current simply because the balance counts against your available credit.
What many people overlook is that cosigning creates a long-term financial bond. You cannot simply remove yourself from the agreement without the lender's consent, and most borrowers cannot refinance the debt without your approval to release you. This means that even years down the road, you may still be tied to someone else's financial decisions. If the primary borrower acquires new debt, loses their job, or goes through a divorce, the ripple effects can land squarely on your shoulders. The emotional temptation to help someone you love can outweigh your awareness of these lingering risks, which is why careful evaluation matters as much as generosity.
 What Happens If You Cosign a Loan and the Other Person Doesn't Pay?
To protect yourself while still being supportive, consider a few straightforward steps. First, ask the borrower to run a credit report with you so you understand the full extent of their current obligations. Second, use an affordability test: simulate what would happen if your income dropped and you had to cover both your expenses and the cosigned payment. Third, put a reminder in your calendar to review the account every few months; checking your own credit report allows you to catch problems early. Finally, calculate a realistic exit strategy, such as agreeing on a timeline when the borrower will refinance on their own, so the arrangement has a clear endpoint from the very beginning.
In the end, cosigning is neither banned from benefiting your credit nor guaranteed to harm it. The outcome hinges almost entirely on how responsibly the primary borrower manages the account and how closely you monitor it. Approaching cosigning with open eyes, honest conversations, and a concrete plan transforms it from a risky gamble into a structured act of support. Take the time to understand the terms, communicate expectations clearly, and protect your own financial health while lifting someone else up. That balance is what makes cosigning a wise choice rather than a regrettable one.