Getting A Car Loan
So, you’re thinking about a car loan. Brave move. It’s a wild ride, and I’m your co-pilot. Let’s be real: buying a car with cash is for unicorns and lottery winners. Most of u...
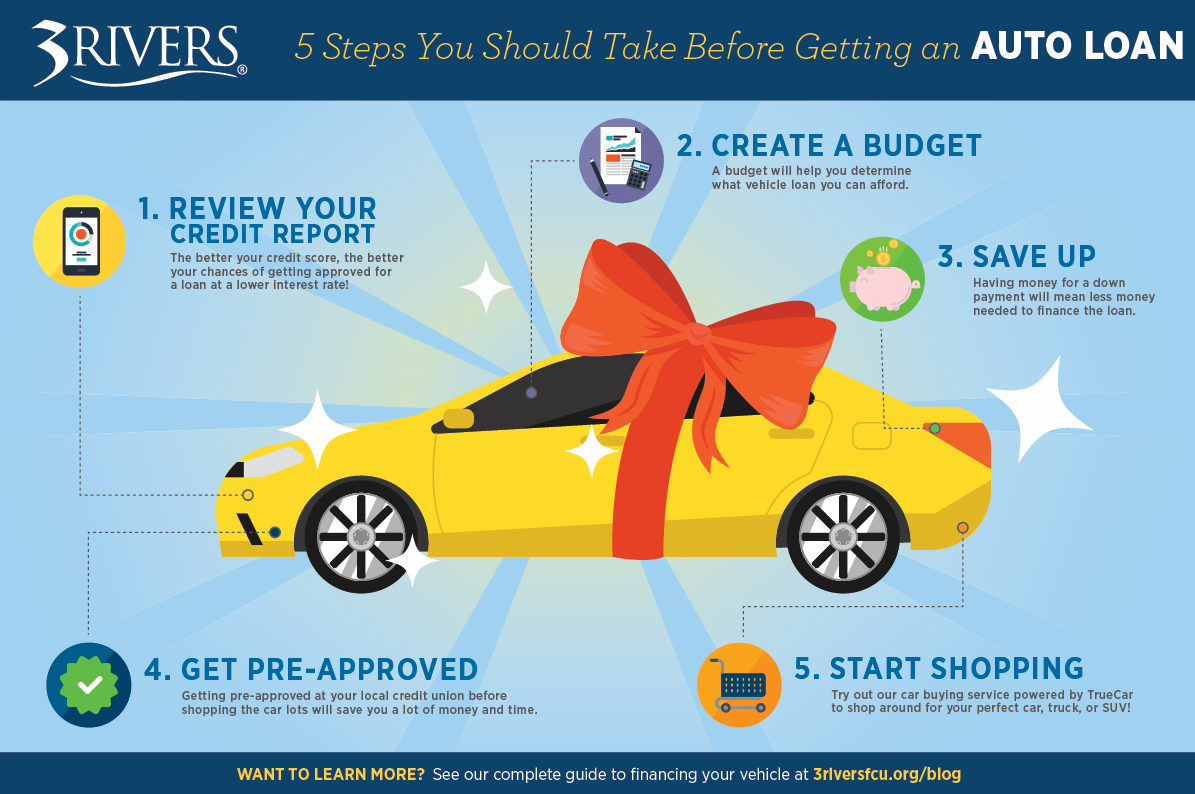
So, you’re thinking about a car loan. Brave move. It’s a wild ride, and I’m your co-pilot.
Let’s be real: buying a car with cash is for unicorns and lottery winners. Most of us need a loan. And that’s okay! It’s a financial adventure, not a punishment.
Step One: Know Your Credit Score
Your credit score is your financial report card. It’s like high school, but with way more interest. This three-digit number determines if you get a sweet 3% rate or a horrifying 25% rate.
Must Read
Check it before you shop. Don’t be that person who walks into a dealership blind. You wouldn’t skydive without checking your parachute, would you?
Fun fact: The highest credit score possible is 850. Nobody has that. It’s like Bigfoot—rumored, but never seen.
Step Two: The Pre-Approval Power Move
Get pre-approved by a bank or credit union before you step onto a car lot. It’s like bringing your own snacks to a movie theater. Way cheaper. Dealers love to mark up rates for profit.
Pre-approval tells you exactly how much you can borrow. It’s a magic number that stops you from falling in love with a $50,000 SUV when your budget says $25,000. Heartbreak doesn’t need to happen.
Quirky reality: Some lenders use a “scorecard” that weighs things like your job stability. Being a professional dog walker? Valid. Just show proof of income.
Step Three: The Loan Term Trap
“Oh, 72 months? That’s just six years!” Wrong. That’s an eternity in car-loan years. Longer terms mean lower monthly payments, but you pay way more in interest over time.
Think of it like buying a pizza on a six-year payment plan. The first slice is delicious, but slice 72 costs you double. Not worth it.
 Buying a Car? Here’s Your Step-by-Step Guide to Getting the Best Car
Fun fact: The average new car loan is now 68 months. That’s almost six years of saying, “Oh, I still owe money on this thing.”
Step Four: The Down Payment Dance
Put money down. I know, it hurts. But a 20% down payment is the golden rule. It shows the bank you’re serious. It also means you’re not “upside down” on the loan—a terrifying term for owing more than the car is worth.
Imagine your car is a toaster. If you borrow $1,000 for a toaster, and it breaks immediately, you still owe $1,000. That’s upside down. Don’t be upside down on a toaster.
Quirky detail: Some dealerships offer zero down payment. Run. It’s a trap for people with great credit who love burning money on interest.
Step Five: The Interest Rate Mystery
Your interest rate is the fee for borrowing money. It’s like the universe charging you for time travel. You get money now, but you pay more later.
Shoot for a rate below 6% if your credit is good. If your credit is “meh,” you might see 10-15%. That’s like paying an extra $200 a month for the privilege of driving.
Fun fact: In 2019, the average car loan interest rate was 4.6%. Today? It’s over 7%. Inflation is a party pooper.
 Car Loan
Step Six: Read the Fine Print
Loans come with sneaky fees. There’s an origination fee, a documentation fee, and sometimes a “prepayment penalty” for paying off your loan early. Yes, that’s a thing. Banks want you to stick around for the full interest ride.
Ask about “GAP insurance.” It covers the difference if your car gets totaled and you owe more than it’s worth. It’s cheap peace of mind.
Quirky reality: Some lenders have a “cooling off” period of three days. You can legally cancel the loan if you change your mind. But act fast. Your new car’s smell can cloud your judgment.
Step Seven: Don’t Be a Finance Ninja
You don’t need to be a math wizard. Just use an online loan calculator. They’re free. Plug in the numbers: car price, down payment, interest rate, term length. It spits out your monthly payment.
Play with it like a video game. See how adding $1,000 to your down payment drops your monthly cost? You love to see it. Curiosity is your best tool.
Final Word: Keep It Fun
Getting a car loan is like learning to ride a bike with training wheels. It’s okay to wobble. The key is to negotiate like you’re at a flea market. Ask for a lower rate. Haggle. You might get laughed at, or you might save $500.
Remember: The salesperson wants to sell you a loan as much as they want to sell you a car. You have power. Use your pre-approval as a shield. Smile. And don’t fall for the “four-square” negotiating tactic—it’s designed to confuse you.
So, go forth. Get that loan. Drive off into the sunset. And when you make your first payment, think of me. I’ll be cheering you on from my own slightly-too-expensive car.
