Goods Available For Sale Formula
The goods available for sale formula is one of the most foundational calculations in inventory management and accounting, and it is widely valued because it gives businesses a...
The goods available for sale formula is one of the most foundational calculations in inventory management and accounting, and it is widely valued because it gives businesses a realistic picture of everything they can sell during a given period. Whether you run a small online store or oversee the warehouse of a major retailer, understanding how to determine the total value of goods sitting on your shelves is essential. This single figure serves as the starting point for computing cost of goods sold, gross profit, and ultimately net income, making it a cornerstone of sound financial planning.
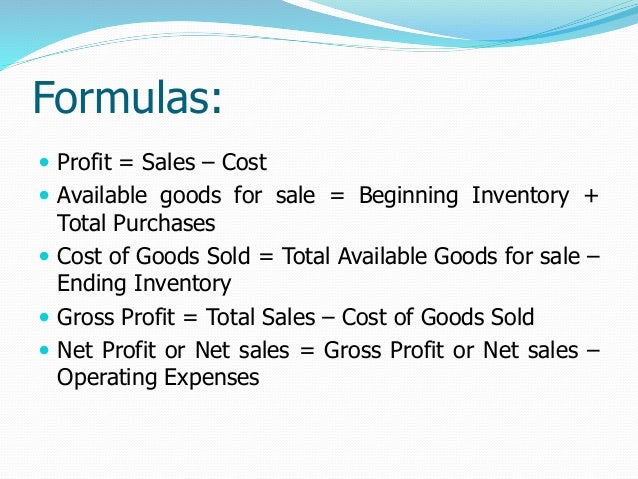
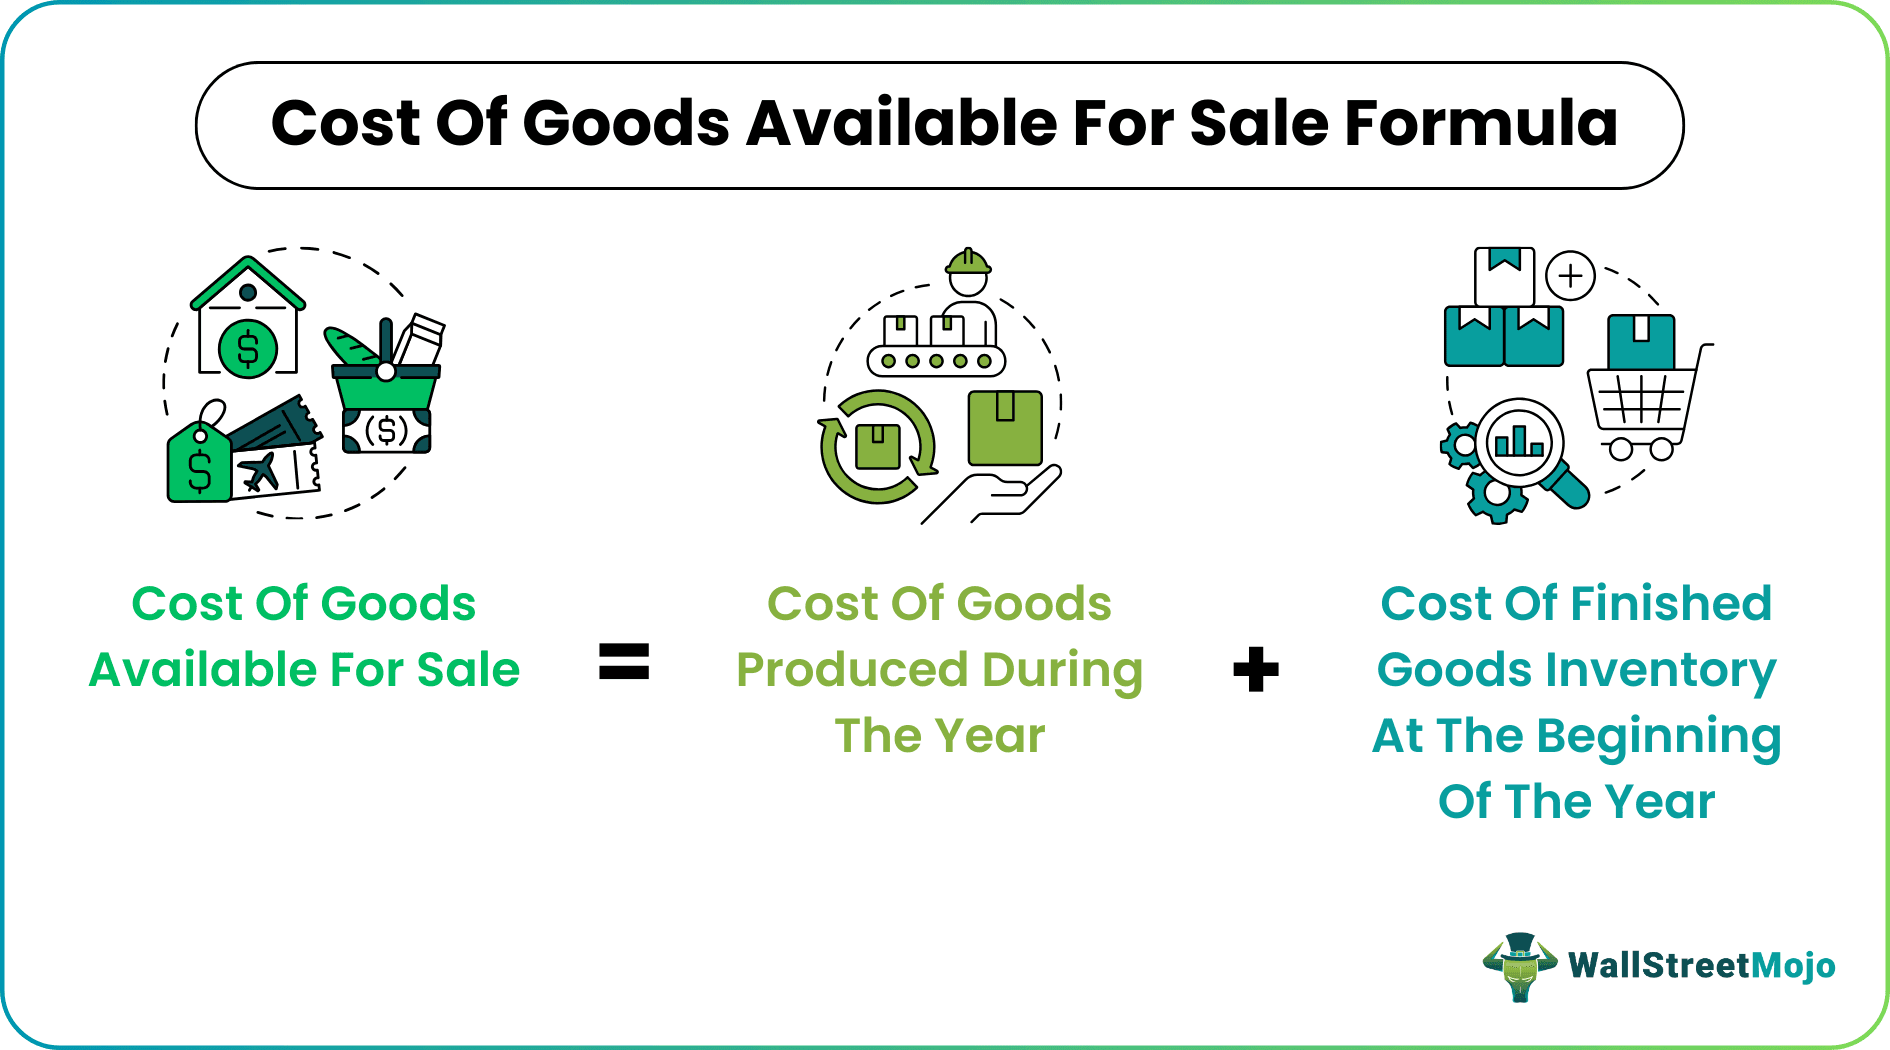
The formula itself is straightforward: Opening Inventory + Purchases = Goods Available for Sale. In simple terms, you take the value of inventory already on hand at the beginning of the period, add the purchasing cost of all new stock acquired during that period, and the result is the total dollar value of everything you have available to sell. While the math is simple, its significance should not be underestimated. This figure acts as an upper limit—no business can sell more value than it actually has on hand, so the number anchors every downstream calculation in your financial statements.
Consider a practical scenario. A bakery starts January with $5,000 worth of flour, sugar, and packaging on the shelves. Throughout the month, its owner purchases an additional $8,000 worth of raw materials. According to the formula, the goods available for sale total $13,000. At the end of January, if a physical count shows that $3,500 of ingredients remain unused, the baker can subtract that ending inventory from the goods available figure to arrive at a cost of goods sold of $9,500. Without first knowing the goods available for sale, the baker would have no reliable benchmark for measuring consumption or profitability.
Must Read
One of the greatest benefits of using this formula in everyday life is the clarity it provides. Retailers, wholesalers, and even freelancers who sell products can use it to track stock levels with confidence. It helps identify shrinkage—the unfortunate reality that inventory sometimes disappears due to theft, damage, or recording errors. When the goods available for sale does not match expected sales plus ending inventory, business owners know immediately that something went wrong in the warehouse. This early warning system protects margins and keeps operations transparent.
 Cost of Goods Available for Sale (Formula, Calculation)
The formula also plays a pivotal role in selecting an inventory valuation method. Businesses commonly choose between FIFO (first in, first out), LIFO (last in, first out), and the weighted average approach. Each method affects how cost is allocated between the goods sold and the inventory that remains, and all three calculations begin with the same goods available for sale figure. In periods of rising prices, for instance, FIFO assigns older, cheaper costs to the goods sold and places newer, pricier costs on the remaining inventory, which can reduce taxable income. Having a reliable goods available for sale baseline allows managers to compare these methods side by side and choose the strategy that best aligns with their financial goals.
If you would like to explore this concept on your own, start by recording your opening inventory value at the beginning of any tracking period and log every purchase with its date and cost. After a month, add the two figures together and verify the result against a physical stock count at period end. Tip: use a simple spreadsheet where each purchase is its own row so you can audit your numbers quickly. Tip: repeat the exercise monthly to build a habit that many seasoned business owners consider indispensable. By practicing the formula regularly, you will develop a strong sense of your business's inventory health and be well prepared for more advanced accounting challenges that follow.