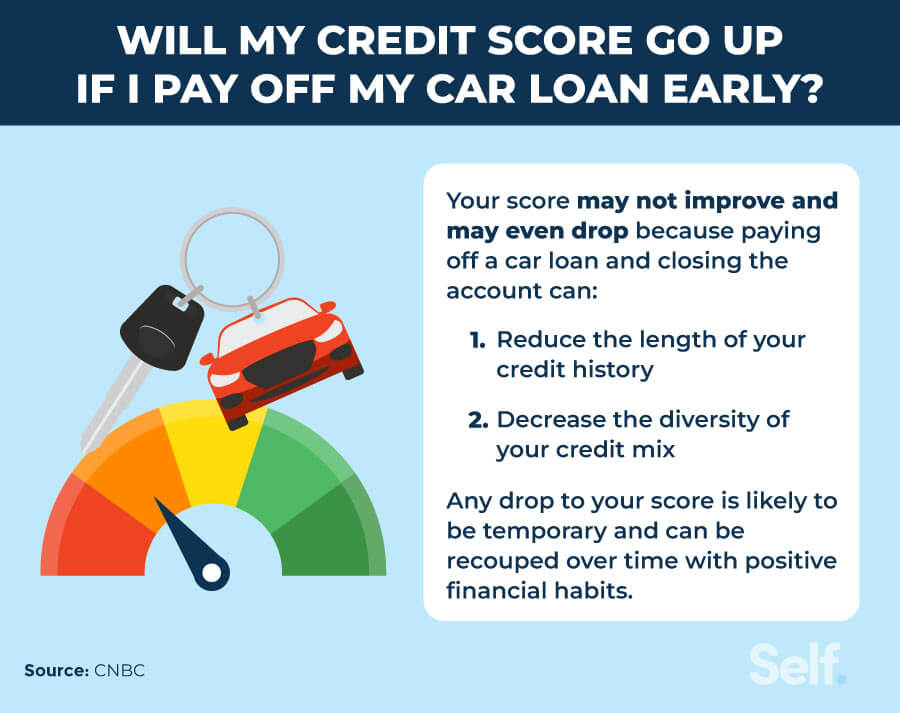
I Paid Off My Car Loan Now What
There are few moments in personal finance that feel as satisfying as paying off a car loan. The relief of knowing a major debt is behind you creates a sense of accomplishment...
There are few moments in personal finance that feel as satisfying as paying off a car loan. The relief of knowing a major debt is behind you creates a sense of accomplishment that many people cherish deeply. As you make that final payment, you move closer to full financial independence. This transition matters because it signals a shift: from living with obligation to enjoying the full value of what you own. For anyone who has spent years balancing monthly payments with everyday expenses, reaching this milestone is genuinely liberating.
Once your car loan is completely paid off, the most important benefit is simply extra money back in your pocket every month. That fixed payment, which may have been hundreds of dollars, suddenly disappears from your budget. Imagine you were paying $400 per month on your vehicle loan — after payoff, that $400 becomes available for savings, investing, or tackling other debts. This newfound financial breathing room is one of the most practical advantages of clearing a car note early. You will feel this impact almost immediately when your bank balance remains higher at the end of each month.
The next essential step is to secure and update your paperwork. Contact your lender as soon as the loan is satisfied and request a formal payoff confirmation or release of lien letter. Take this document to your local Department of Motor Vehicles or equivalent authority, because your title may still carry the lender's name. Having a clean, lien-free title in your possession ensures that nobody else has a legal claim to your vehicle. This step also protects you if you plan to sell or trade the car in the future — dealers and private buyers will want to see that the title is clear and unencumbered.
Must Read
With a lien-free title, you also gain the freedom to adjust your insurance coverage. While the car was financed, your lender likely required comprehensive and collision insurance to protect their investment. Now that you own the vehicle outright, you can choose to reduce coverage or increase deductibles. If your car is older and its market value has declined, paying for full coverage may no longer make financial sense. Evaluate the replacement value of the vehicle versus the premium you pay each month, and decide whether a leaner policy better suits your current financial situation.
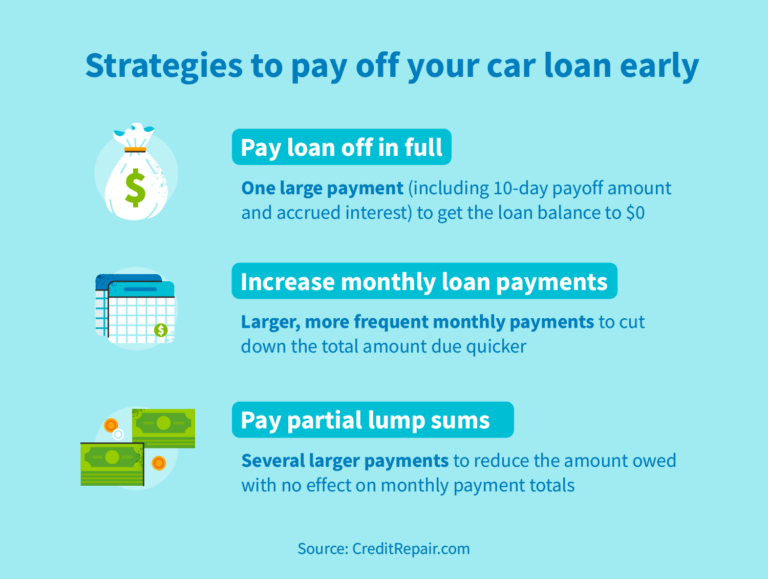 Should I pay off my car loan early? - CreditRepair.com
Some people immediately consider upgrading their car once a loan is paid off. While it is tempting, a more strategic choice is to redirect that monthly payment toward your next financial goal. Consider accelerating payments on a credit card balance, building an emergency fund, or contributing more to a retirement account. For instance, if you inherit a $400 monthly budget, putting it into a high-yield savings account could generate noticeable returns over a few years. This approach transforms the discipline you already built into real wealth-building momentum rather than simply upgrading to a newer model.
Finally, take a moment to reflect on the discipline that brought you to this milestone. Managing consistent vehicle payments requires budgeting awareness and long-term commitment, and those skills extend well beyond a single auto loan. One simple tip for readers is to automate regular contributions to savings using the exact amount you freed up from your car payment — your own brain will adjust to the budget without friction. Another helpful practice: set a modest monthly date to review your bank statements and track your progress. These small but consistent habits ensure that paying off your car loan becomes not just a celebration, but the foundation of stronger financial health for years to come.