Is $10 Million Enough To Retire At 30
The dream of early retirement has captivated millions of people across the globe, thanks in large part to the financial independence movement and the rise of billionaires who...
The dream of early retirement has captivated millions of people across the globe, thanks in large part to the financial independence movement and the rise of billionaires who seem to have figured out the ultimate shortcut to freedom. The idea of walking away from work at age 30 with a seven-figure (or eight-figure) nest egg sparks endless debate among financial advisors, early retirees, and everyday professionals alike. But the question that keeps emerging on forums, podcasts, and dinner tables is deceptively simple: Is $10 million enough to retire at 30? Understanding this question matters because the answer reshapes how we think about wealth, work, and what it truly means to live well.
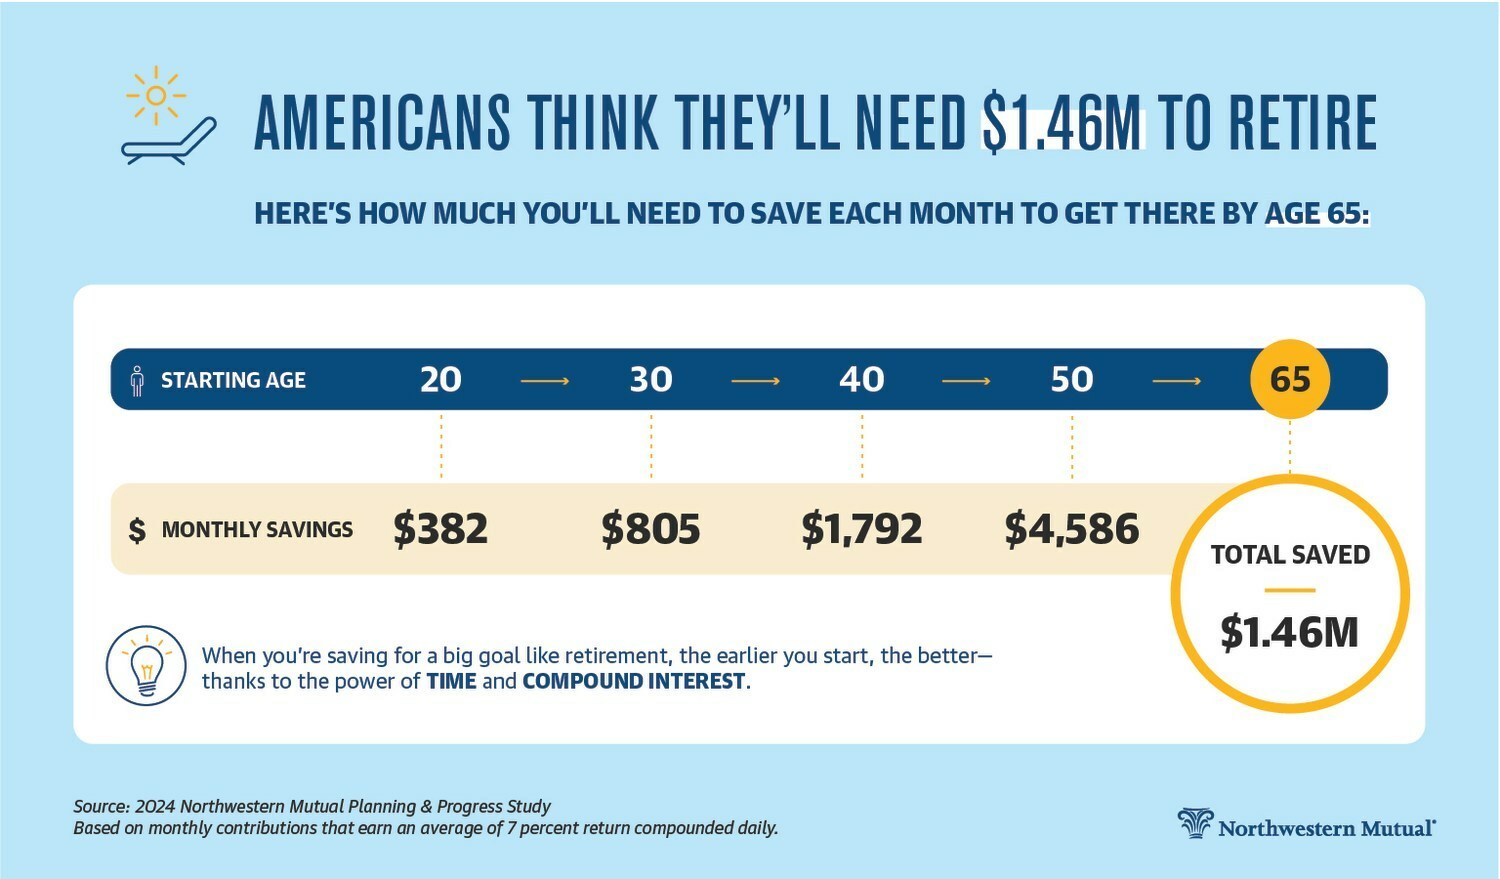
The number itself sounds extraordinary to most people—ten million dollars is roughly 50 to 100 times the median household income in the United States. At first glance, it seems like an untouchable safety net. Using the widely referenced 4% rule, a $10 million portfolio would generate approximately $400,000 per year before taxes. That amount alone puts a retiree comfortably above the national average income, covering food, housing, healthcare, and leisure for a typical household. In this scenario, passive income from index funds, dividends, or bond yields could sustain the lifestyle indefinitely, provided the portfolio is managed wisely and the markets behave reasonably over a long horizon.
However, reality is far more nuanced than a simple multiplication exercise. Lifestyle inflation is one of the biggest silent threats to early retirees. Consider someone who purchases a $3 million home, maintains luxury vehicles, takes international vacations twice a year, and enjoys fine dining—suddenly, annual expenses can easily top $300,000. Add in private schooling for children, philanthropy, or mounting healthcare premiums at a young age, and the margin of error narrows considerably. Additionally, taxes on investment gains, long-term capital gains rates, and potential changes in tax legislation can significantly erode what's left in the account each year. Without careful planning, the $400,000 annual yield may shrink to $280,000 or less after taxes.
Must Read
Another critical factor is the time horizon. Retiring at 30 means the money must last potentially 60 years or more—an extraordinarily long investment period. Inflation, even at a moderate 3% annually, reduces purchasing power by more than 80% over six decades. A dollar saved in 2024 would be worth only about 17 cents in 2084. This means the portfolio must not only provide income but also grow consistently faster than inflation to preserve real wealth. Sequence-of-returns risk—the danger of major market downturns in the early years of retirement—can also be devastating if withdrawals occur during a bear market, permanently shrinking the capital base.
On the other hand, there are real scenarios where $10 million is more than sufficient. If a retiree lives modestly, generates supplemental income from a passion project, or relocates to a lower-cost region, the portfolio lasts remarkably long. Someone spending $150,000 a year, living in a mid-sized city, and earning even $50,000 from part-time consulting or rental properties is in an exceptionally strong position. Furthermore, having $10 million creates a powerful buffer against medical emergencies, economic recessions, and unexpected life events like divorce or litigation. The peace of mind this provides is itself a benefit that transcends the numbers.
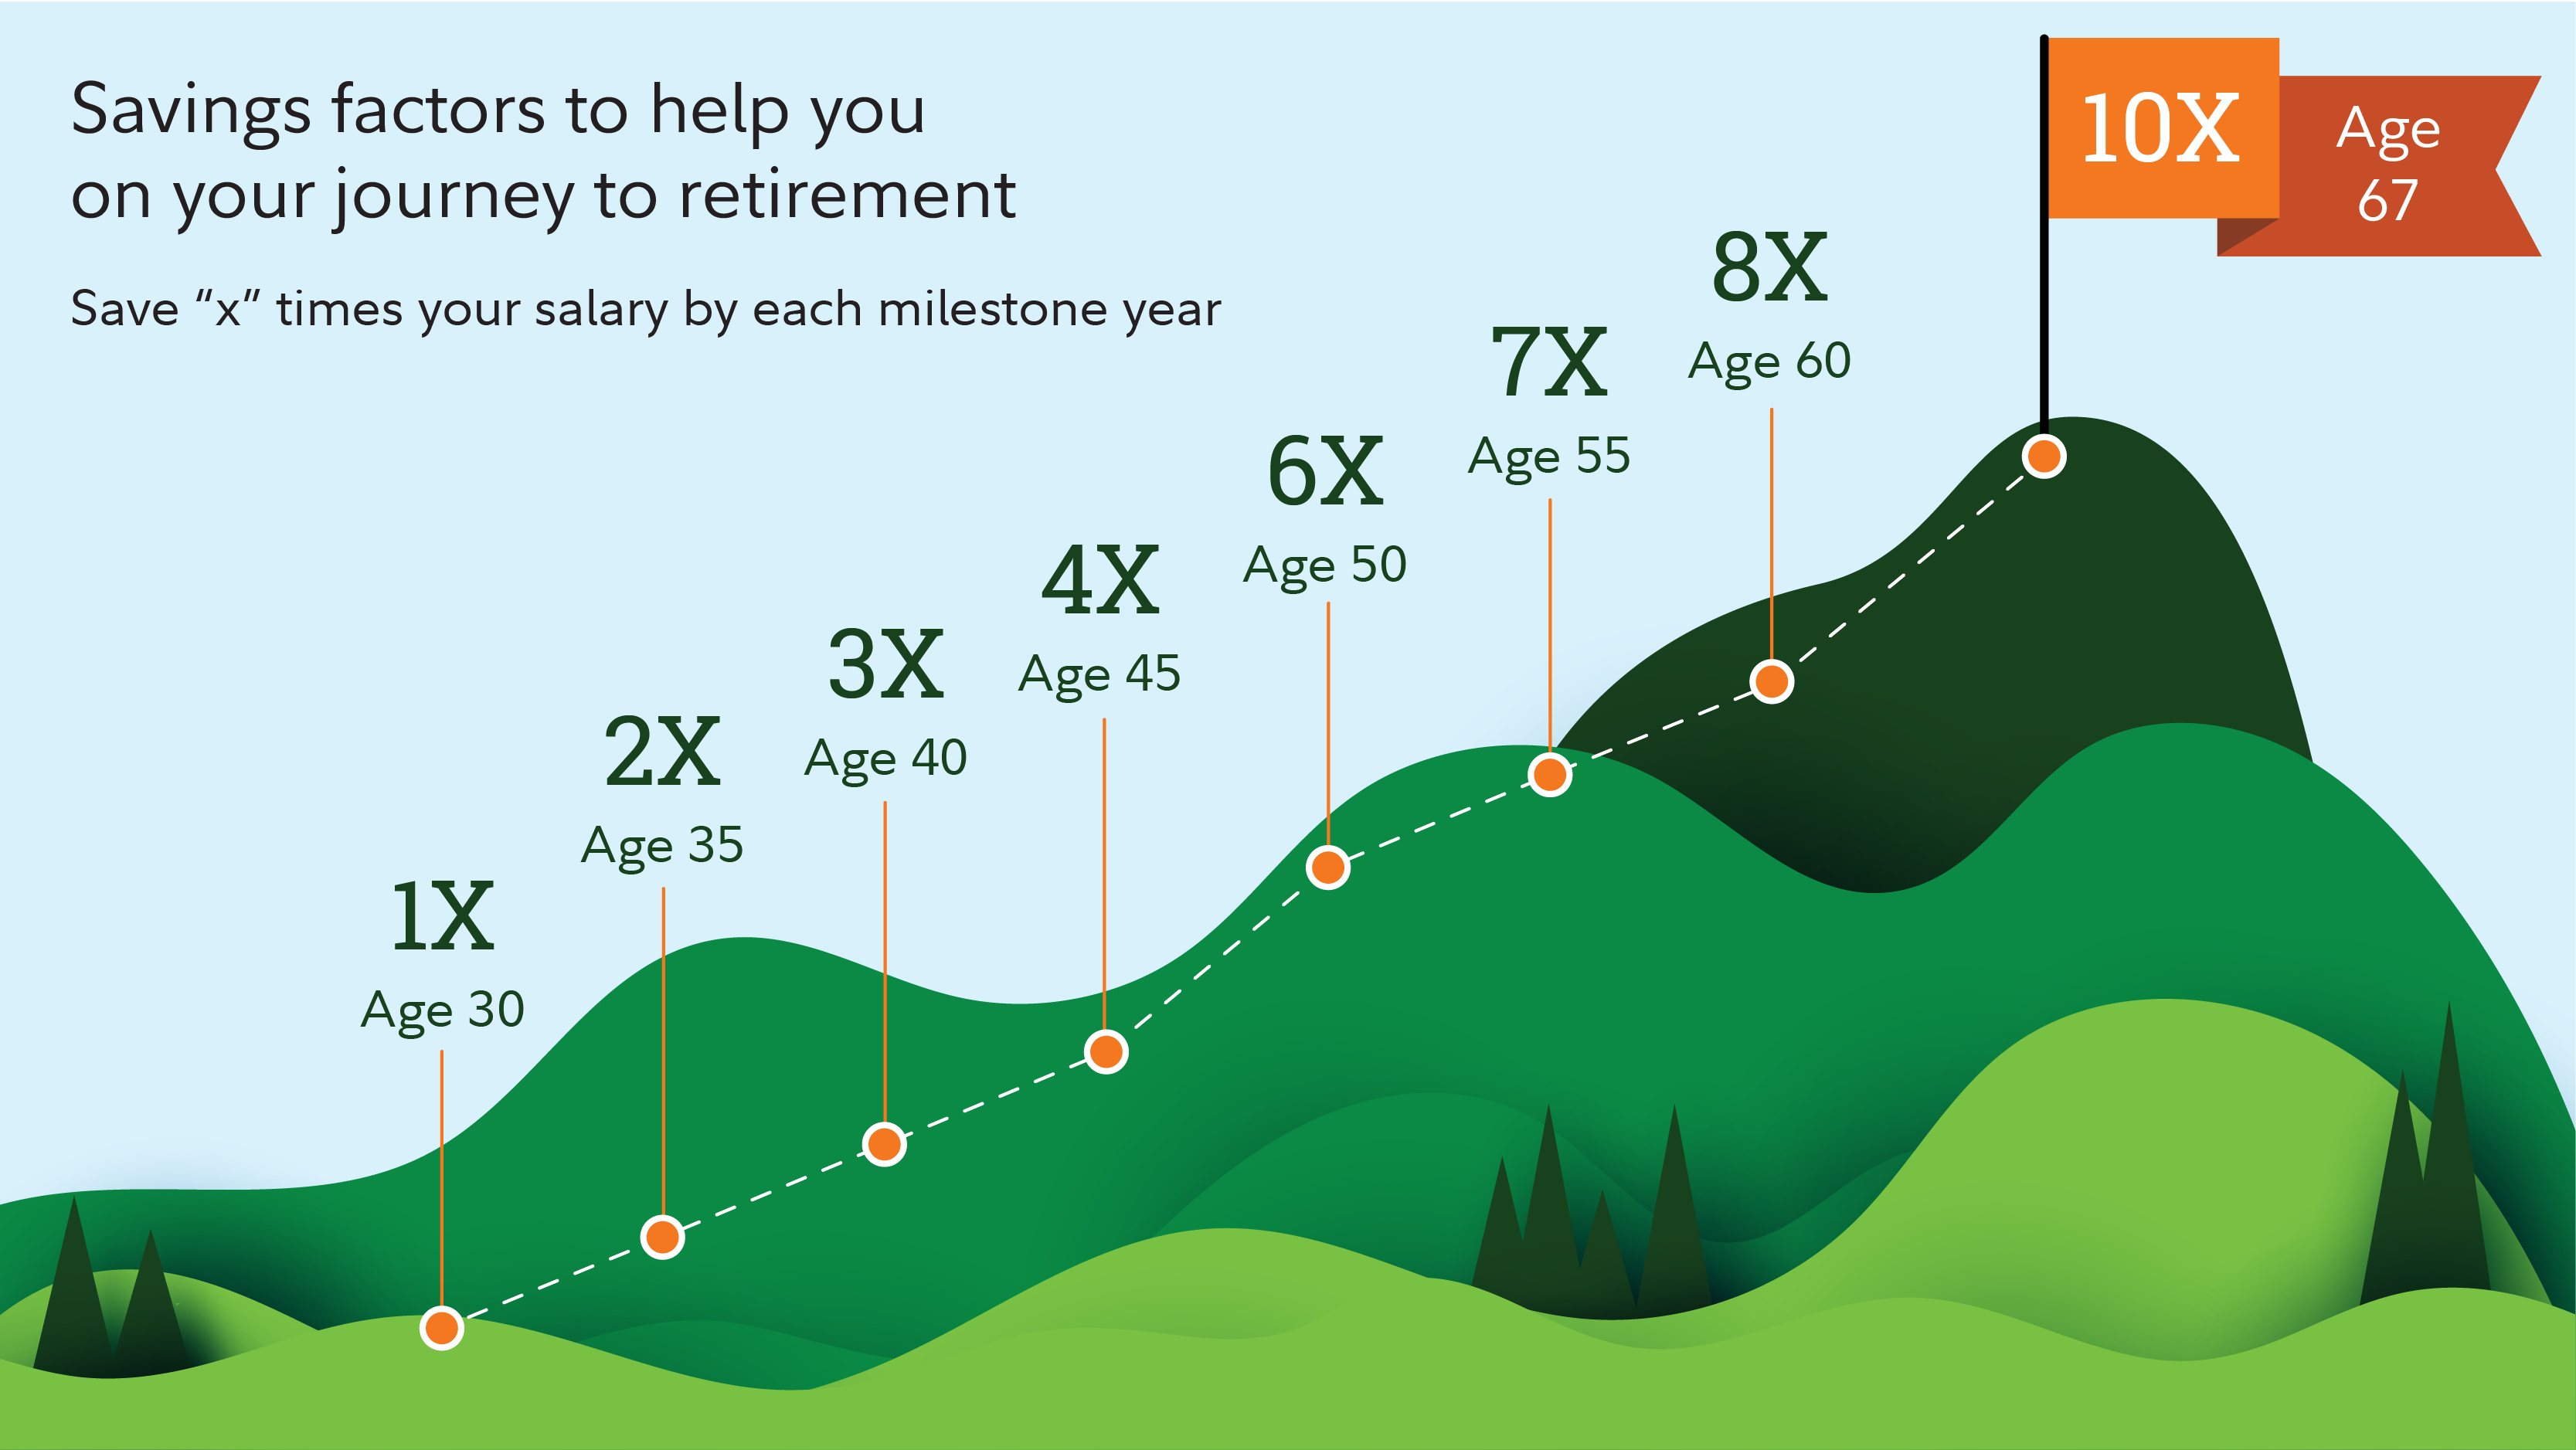 How much do I need to retire? | Fidelity
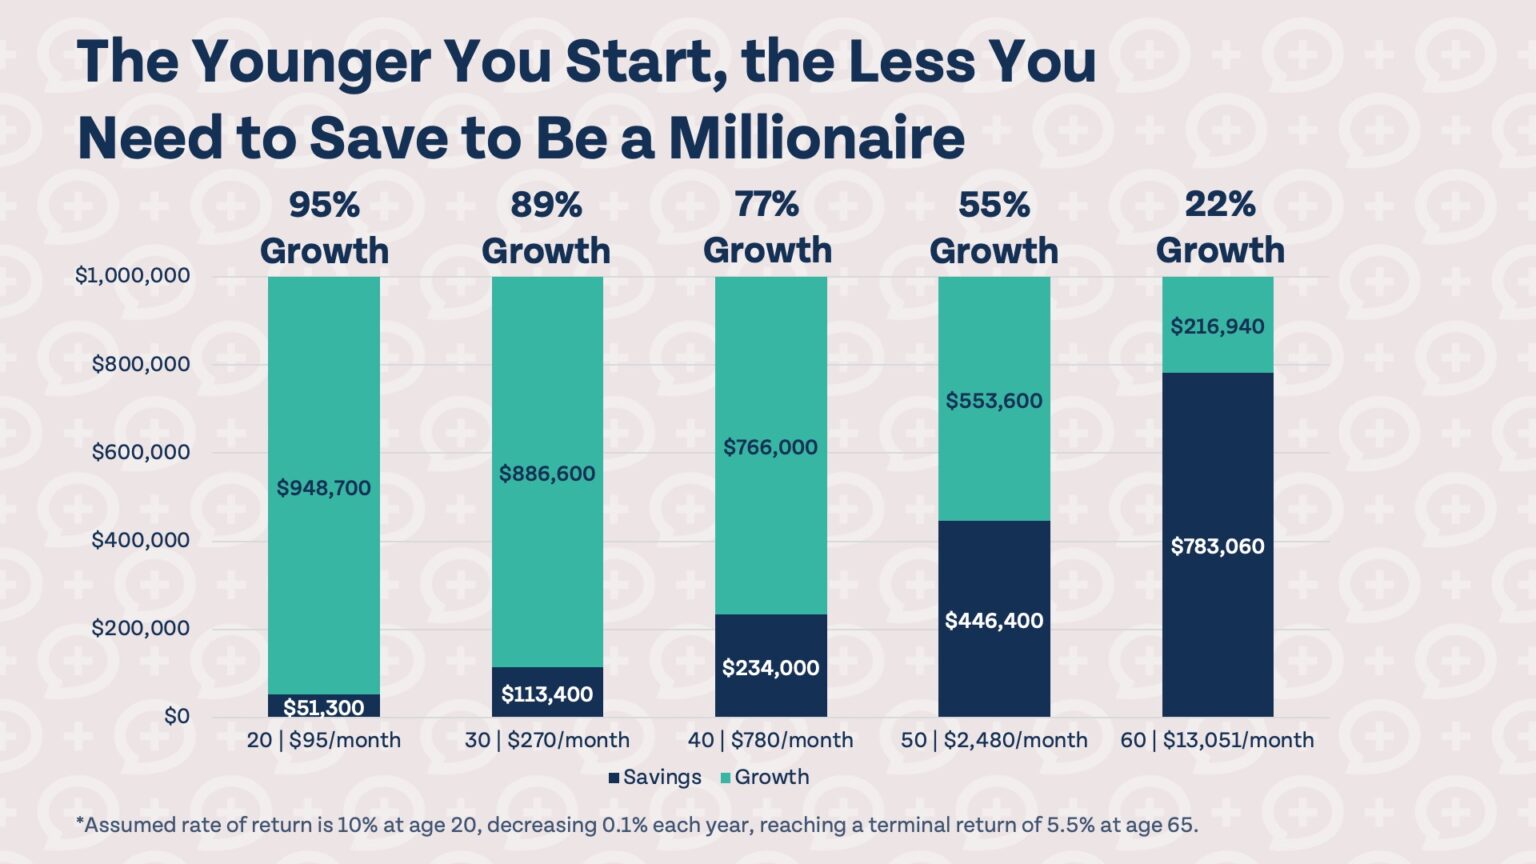
So what practical steps can aspiring early retirees take to ensure $10 million truly covers their future? First, track every expense for at least six months to understand your actual spending norms, not an idealized version. Second, build a detailed retirement calculation using conservative return assumptions (5–6% real growth, not 10%), high-end inflation estimates (4–5%), and realistic tax rates. Third, consider maintaining a cash buffer of one to two years' expenses to avoid selling investments during market dips. Finally, factor in an ongoing desire to contribute—whether through volunteering, creative work, or a small business—because purpose and structure are as essential to retirement longevity as financial math.
Ultimately, $10 million at age 30 is enough for most people—but only if treated with the same discipline required to earn it in the first place. The number is generous, yet not immune to gradual erosion from inflation, taxes, lifestyle creep, and poor decisions. The real lesson is that quantum of wealth matters less than clarity of plan. Those who know exactly what they want, spend intentionally, and invest conservatively will likely find that $10 million buys not just decades of comfort, but the freedom to reinvent themselves entirely.