My Father Is Top Investor
There’s something genuinely enjoyable about watching someone who just gets money. It’s not about the numbers on a screen or the fancy cars—it’s about the quiet confidence of k...
There’s something genuinely enjoyable about watching someone who just gets money. It’s not about the numbers on a screen or the fancy cars—it’s about the quiet confidence of knowing where to put your chips. That’s why the topic of investing, especially when you have a front-row seat to a master at work, feels so practical and widely appreciated. Whether you’re saving for a house, planning for retirement, or just trying to make your paycheck stretch a little further, learning how money can work for you is a game-changer. My father isn’t a billionaire or a hedge fund manager, but he’s a top investor in his own right—and he’s taught me that the real payoff isn’t just wealth; it’s peace of mind.
The main purpose of being a top investor, as my dad shows, is to turn uncertainty into opportunity. It’s not about gambling on hot tips or chasing the latest meme stock. Instead, it’s about building a system that steadily grows your resources over time. The benefits ripple out to everyone: retirees get a steady income, young families can afford a home, and even someone starting with a small salary can watch a little discipline snowball into something substantial. My dad always says, “You don’t need to be rich to invest; you need to invest to be rich.” That mindset alone has helped me sleep better at night, knowing our family has a cushion against life’s surprises.
You’ve probably seen common variations of this approach in action. Think of the friend who always buys index funds and ignores the stock market’s daily drama—that’s a passive investor, like my dad’s early years. Or maybe you know a neighbor who reads earnings reports and flips houses on weekends—that’s an active investor, someone who thrives on research and hustle. My father is a blend of both: he has a core portfolio of boring, reliable ETFs (like a safety net), and he sets aside a small “fun fund” to try out smaller, riskier bets—like backing a local cafe that eventually took off. These variations show that investing isn’t one-size-fits-all; it’s about what fits your personality and goals.
Must Read
The most practical lesson I’ve learned is that getting started doesn’t require a fortune. You can begin today with as little as $20. My dad’s first tip is to automate your savings. Set up a transfer from your checking account to an investment account right after payday—before you can spend it. Even $50 a month, tucked into a broad market fund like an S&P 500 tracker, adds up surprisingly fast thanks to compound interest. The earlier you start, the more time your money has to grow, like rolling a snowball down a long hill. He calls this “paying yourself first,” and it’s so simple that it feels almost like cheating.
Another actionable tip my dad swears by is to ignore the noise. The news is designed to scare you into click, not to make you rich. When the market drops—and it will—his rule is simple: don’t panic-sell. Instead, buy a little more if you can, because you’re getting stocks on sale. He reminds me that even the best investors look like fools in the short term. The key is to focus on the long game, like planting a tree and waiting for it to bear fruit. This patience is what separates a top investor from someone who chases quick wins and usually loses.
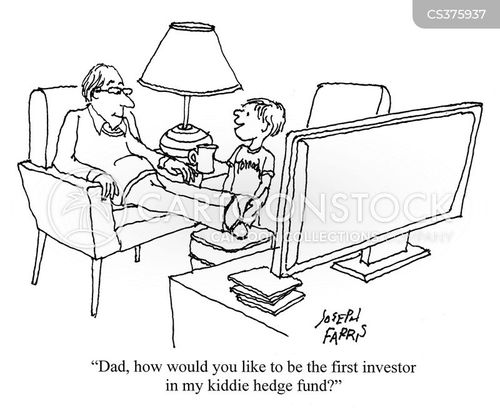
 I am not self made. My father was the 1st investor in my first real
To make the most of it, my father also recommends learning one thing at a time. You don’t need to understand options trading or cryptocurrency to be successful. Start with simple concepts: what is a stock? What’s a bond? How do dividends work? He used to have me follow a single company’s stock for six months, just to watch how news and earnings affected its price. That small habit taught me more than any finance course. And if you can, find a mentor—someone like my dad who’s been through crashes and booms—and ask them honest questions. Most top investors love sharing what they know.
Ultimately, having a father who’s a top investor has shown me that this journey isn’t about being a genius—it’s about staying the course. The benefits—financial security, less stress, and the freedom to make choices—are available to anyone willing to start small and think long-term. So whether you’re already dabbling in stocks or just curious about where to begin, channel your inner investor: automate, ignore the noise, and keep learning. You don’t need perfect timing—you just need to start, and let time do the heavy lifting.