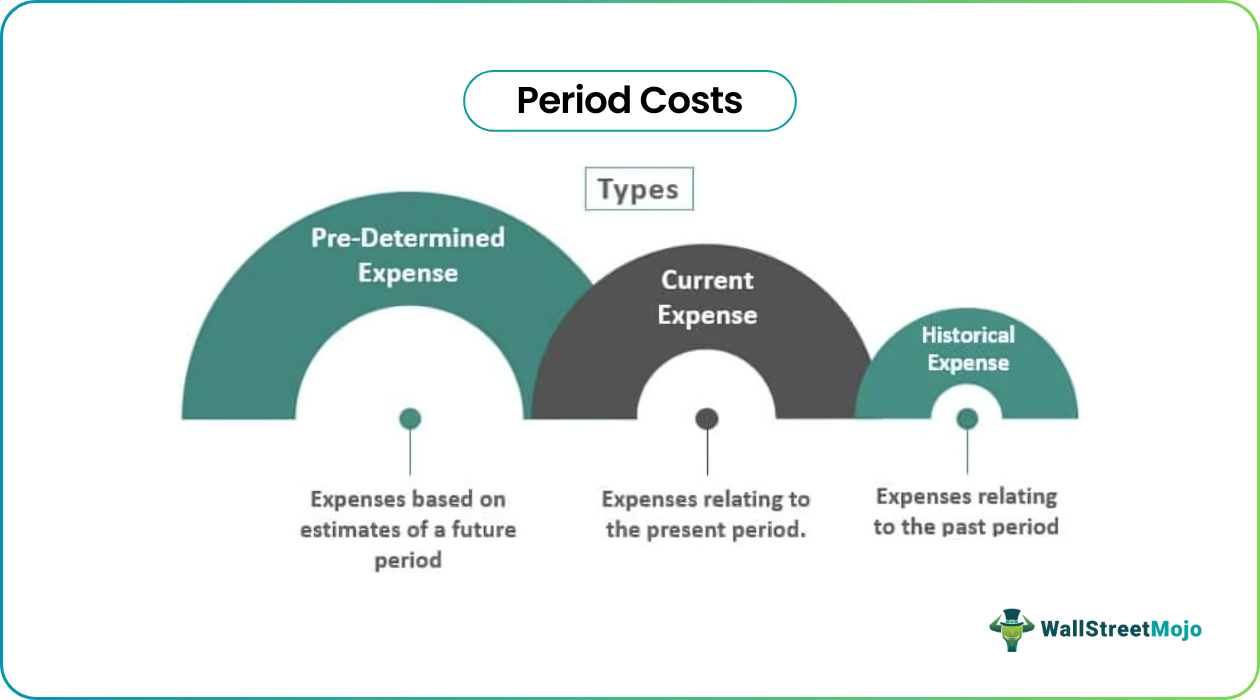
What Are Period Costs In Accounting
Understanding period costs is one of the most satisfying aspects of learning accounting, because it transforms abstract numbers into a language that everyone can use. When you...

Understanding period costs is one of the most satisfying aspects of learning accounting, because it transforms abstract numbers into a language that everyone can use. When you see how these costs flow through a company’s income statement, you realize that the same principles help a family budget for vacation or a freelancer decide which software subscription to keep. The appeal lies in the clarity: once you grasp a period cost, you can predict cash flows, spot waste, and make smarter choices in everyday life.
Period costs are expenses that are recorded on the income statement in the period they are incurred, rather than being attached to a specific product. Their key purpose is to allocate the cost of running the business over time, ensuring that the financial statements reflect the company’s true profitability for a given month, quarter, or year. By expensing them immediately, accountants can show how much a firm spends on operating activities—like rent, utilities, or salaries—without waiting for the goods to be sold.
What makes period costs distinct is that they are not part of the cost of inventory. Unlike product costs, which are capitalized and only recognized as cost of goods sold when the finished item leaves the warehouse, period costs are treated as expenses as soon as they occur. This treatment follows the matching principle: costs are recorded in the same timeframe as the revenues they help generate. For example, a manufacturing plant’s factory rent is a period cost because the rent supports the production environment for the whole month, regardless of how many units were crafted.
Must Read
Everyday decisions benefit from this clarity. Suppose you own a small bakery. Your monthly advertising bill—say, $500 for social‑media ads—is a period cost. You can compare that expense directly against the sales increase it produced in the same month, rather than waiting for the cookies to sell to see the impact. This real‑time insight lets you adjust your marketing budget on the fly, much like a household might cancel a streaming service that no longer adds value. The principle helps both businesses and individuals keep a tight grip on cash outflows.
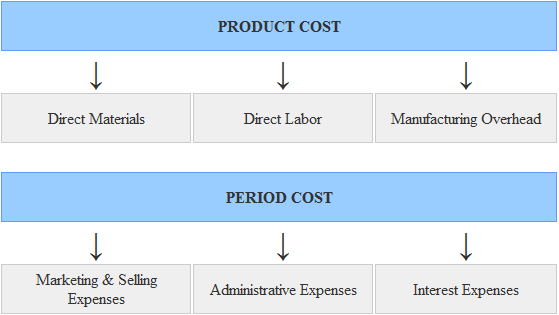 Product costs and period costs - explanation and examples | Accounting
Consider a startup launching a new app. The founders decide to spend $2,000 on a one‑off conference booth. Because the booth expense occurs before any product is sold, it is recorded as a period cost for the conference month. The founders can then examine the conference’s lead generation results side‑by‑side with the cost, deciding whether the booth paid off in new users. This direct comparison simplifies evaluating external initiatives, giving you a clear picture of where resources are earning their keep.
To explore period costs on your own, start by picking a routine expense—your monthly gym membership, a subscription to a design tool, or a recurring electricity bill. Ask the following questions: When is this cost incurred? Does it relate to inventory? How does it align with the revenue earned that period? Use a simple spreadsheet to log each expense in the month it appears on your bank statement. Next, compare those entries with the revenues generated in the same period. Finally, experiment by categorizing the expense as a product cost versus a period cost to see how the financial picture changes. These hands‑on steps turn textbook concepts into practical habits you can apply to any budget or business plan.