What Is A Finance Charge On My Credit Card
Let’s be honest—credit card statements can sometimes feel like they’re written in a secret code. But among the jargon, there’s one term that’s surprisingly practical and even...
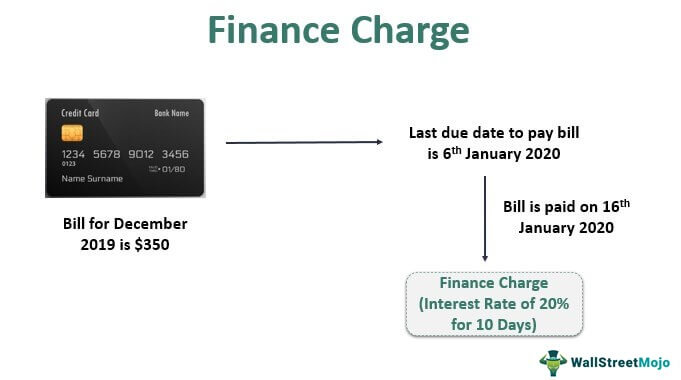
Let’s be honest—credit card statements can sometimes feel like they’re written in a secret code. But among the jargon, there’s one term that’s surprisingly practical and even a little satisfying to understand: the finance charge. Think of it as the cost of borrowing money when you don’t pay your full balance by the due date. The best part? Once you know how it works, you can save real money and feel more in control of your finances. It’s like learning the rules to a game you’re already playing—and suddenly, you start winning.
At its core, a finance charge is simply the price you pay for using the credit card company’s money. If you carry a balance from month to month, the issuer charges you interest on that amount. This interest is usually calculated using your annual percentage rate (APR) and your average daily balance. For example, if you have a $1,000 balance with a 20% APR, you could end up paying roughly $16 or more in finance charges for just one month. That’s money you could have spent on coffee, books, or a fun night out. The key insight here is that paying even a little extra each month can dramatically reduce those charges.
Different people get different benefits from understanding finance charges. For budget-conscious students, it’s a wake-up call to avoid the debt spiral. For busy professionals, it’s a tool to decide whether to pay off a big purchase now or finance it over time. And for travel rewards enthusiasts, knowing how to avoid finance charges means they can rack up points without paying a cent in interest—just by paying their full statement balance each month. In fact, many savvy users set up automatic payments to ensure they never miss a due date, turning their card into a free short-term loan.
Must Read
You’ve probably seen a few variations of finance charges in action. The most common is the standard interest charge on unpaid balances. But there’s also the cash advance fee—which starts accruing interest immediately, often at a higher rate—or the balance transfer fee, usually a percentage of the amount moved. Some cards even have a minimum finance charge (like $2), so a tiny unpaid balance can still cost you. Recognizing these variations helps you avoid nasty surprises. For instance, you might think a balance transfer is free, but that 3% fee is technically a finance charge too.
 How to Calculate the Finance Charge on a Credit Card Balance
So how do you make the most of this knowledge? Here are a few simple, actionable tips. First, always pay your full statement balance by the due date—this is the golden rule. If you can’t, pay as much as possible and pay more than the minimum. Second, check your card’s APR and understand how your issuer calculates the daily balance (most use the average daily balance method). Third, set up payment reminders or automatic payments to avoid late fees, which can trigger even higher finance charges. Finally, consider a 0% APR introductory offer for big purchases, but read the fine print—the charge can retroactively apply if you’re late.
In the end, a finance charge is not your enemy—it’s just a signal. It tells you exactly how much it costs to borrow, which lets you make smarter choices. Whether you’re saving for a trip, building credit, or just avoiding unnecessary fees, understanding this simple concept puts you in the driver’s seat. Next time you see that line on your statement, you’ll smile—because you’ll know exactly what to do about it. And that’s a feeling worth more than any number on a bill.
